
Life insurance is a crucial financial product that provides peace of mind and financial security to individuals and their families. However, with the rise of fraudulent schemes and scams, it’s natural to question the legitimacy of certain insurance providers.
One such company that has faced scrutiny is Senior Life Insurance Company. There have been concerns and rumors circulating about whether Senior Life Insurance Company operates as a pyramid scheme. In this blog post, we’ll delve into the details to answer the question: Is Senior Life Insurance Company a pyramid scheme?
We’ll also explore the business model of Senior Life Insurance Company, clarify what a pyramid scheme entails, and provide insights to help you differentiate between legitimate insurance providers and fraudulent schemes. Let’s have a look together!
Understanding Pyramid Schemes
Before exploring the specifics of Senior Life Insurance Company, it’s crucial to understand what a pyramid scheme is and how it operates.
Pyramid schemes are illegal in many countries, including the United States, due to their deceptive nature. These schemes often promise high returns for a minimal investment, but they rely on recruiting new members to bring in money rather than selling a legitimate product or service.
In a pyramid scheme, participants are typically asked to make an initial investment, and then they are encouraged to recruit others to join the scheme. As new members join, the original members receive a portion of their investment. This process continues, with each new member required to recruit additional participants to generate returns for those at the top of the pyramid.
The problem with pyramid schemes is that they are unsustainable. Eventually, they collapse because it becomes impossible to recruit enough new members to continue generating returns for existing members. When the scheme collapses, the majority of participants lose their investment.
It’s important to note that not all multi-level marketing (MLM) companies are pyramid schemes. While MLMs also rely on recruitment, they differ from pyramid schemes in that they offer a legitimate product or service for sale. Participants in MLMs can earn money through the sale of products, not just by recruiting new members.
Senior Life Insurance Company Overview
Senior Life Insurance Company, also known as Senior Life Insurance Company of America (SLICA), is a well-established insurance provider that specializes in offering final-expense life insurance to seniors. The company has been in operation for several decades and has built a reputation for providing affordable and reliable insurance coverage.
Senior Life Insurance Company primarily focuses on serving the senior population, offering insurance policies that are specifically designed to help cover final expenses such as funeral costs, medical bills, and other end-of-life expenses. These policies are often referred to as burial insurance or final expense insurance.
One of the key features of Senior Life Insurance Company’s policies is that they are typically easier to qualify for compared to traditional life insurance policies. This makes them an attractive option for seniors who may have difficulty obtaining coverage elsewhere due to age or health issues.
Moreover, Senior Life Insurance Company operates in multiple states across the United States and has a network of agents who work directly with clients to provide personalized insurance solutions. The company is known for its commitment to customer service and for offering comprehensive insurance products that meet the needs of seniors and their families.
Secure Your Family's Future with Confidence
Don’t leave your loved ones' financial security to chance. Use our expert tools and free resources to find the perfect coverage today.
Is Senior Life Insurance Company a Pyramid Scheme?
No, Senior Life Insurance Company is not a pyramid scheme. It is a legitimate insurance provider that offers final expense life insurance to seniors. Unlike pyramid schemes, which rely on recruitment for revenue, Senior Life Insurance Company generates revenue through the sale of insurance policies.
These policies provide financial protection to policyholders and their beneficiaries in the event of the policyholder’s death. While there may be skepticism surrounding certain insurance providers, Senior Life Insurance Company operates within the boundaries of the insurance industry and provides valuable insurance products to its customers.
Senior Life Insurance Company’s Business Model
Senior Life Insurance Company operates as a traditional insurance provider, offering final expense life insurance to seniors. The company’s business model revolves around selling insurance policies that provide financial protection to policyholders and their beneficiaries in the event of the policyholder’s death.
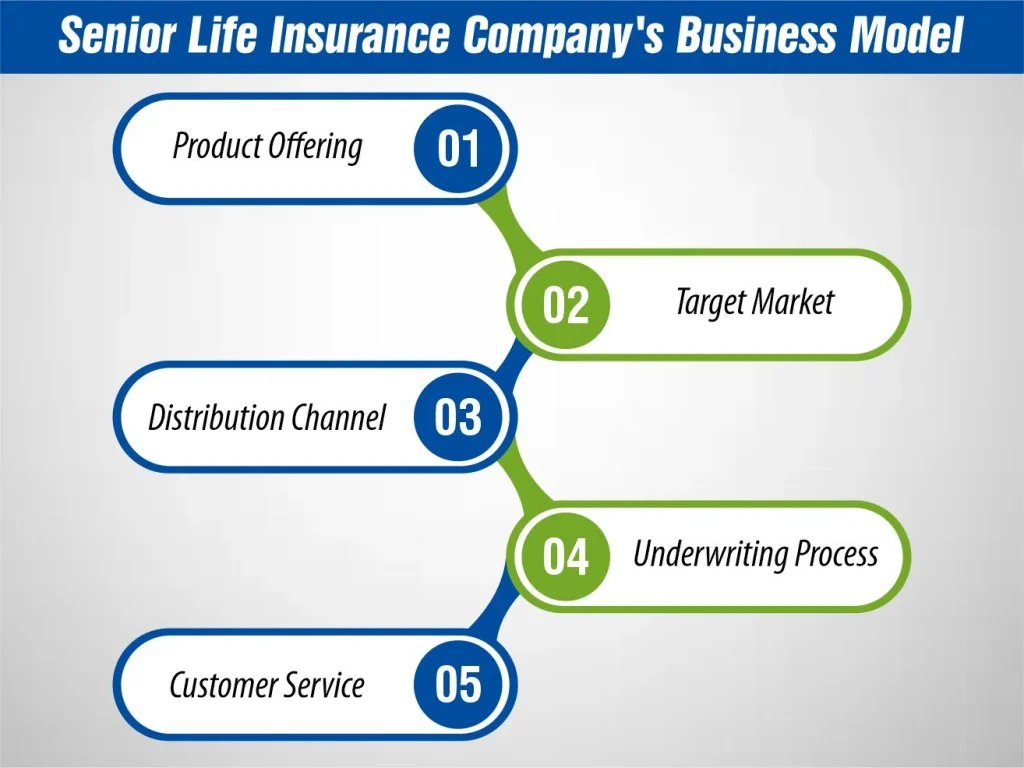
Here’s a breakdown of Senior Life Insurance Company’s business model:
- Product Offering
Senior Life Insurance Company primarily offers final expense life insurance policies. These policies are designed to cover the costs associated with a policyholder’s funeral, medical bills, and other end-of-life expenses.
- Target Market
The company focuses on serving the senior population, as seniors are often more concerned about ensuring their final expenses are covered and may have difficulty obtaining coverage from other insurance providers due to age or health issues.
- Distribution Channel
Senior Life Insurance Company sells its insurance products through a network of agents. These agents work directly with clients to assess their insurance needs and recommend the most suitable insurance solutions.
- Underwriting Process
The company’s underwriting process is tailored to seniors, making it easier for them to qualify for coverage compared to traditional life insurance policies. This approach allows more seniors to obtain the insurance coverage they need.
- Customer Service
Senior Life Insurance Company is known for its commitment to customer service. The company’s agents provide personalized service to clients, helping them understand their insurance options and select the right coverage for their needs.
Essentially, Senior Life Insurance Company’s business model focuses on providing affordable, accessible, and customer-oriented insurance products to seniors.
Why the Confusion?
The confusion about whether Senior Life Insurance Company operates as a pyramid scheme may stem from misconceptions about how insurance companies operate, as well as general skepticism about financial products and services. Here are some reasons why there may be confusion:
1- Lack of Understanding
Many people are unfamiliar with how insurance companies operate and may mistakenly believe that all insurance companies, including Senior Life Insurance Company, function like pyramid schemes. This lack of understanding can lead to confusion and misinformation.
2- Similar Terminology
The terminology used in the insurance industry, such as “recruitment” (agents recruiting policyholders) and “downline” (policyholders and their beneficiaries), may be similar to the terminology used in pyramid schemes. This similarity in terminology can create confusion and lead to false assumptions about the nature of the business.
3- Negative Perceptions
There is a generally negative perception of insurance companies and financial institutions, with many people viewing them as profit-driven entities that prioritize their bottom line over the well-being of their customers. This negative perception can lead to suspicion and skepticism about the legitimacy of companies like Senior Life Insurance Company.
4- Misinformation
In some cases, misinformation or false claims may be spread about Senior Life Insurance Company, leading to confusion and uncertainty about the company’s business practices.
How to Differentiate Between a Pyramid Scheme and a Legitimate Business?
Differentiating between a pyramid scheme and a legitimate business is crucial to avoid falling victim to fraudulent schemes. Here are key factors to consider when distinguishing between the two:
- Product or Service Focus
Legitimate businesses focus on selling products or services to generate revenue. In contrast, pyramid schemes often emphasize recruiting new members to bring in money, with little or no emphasis on selling a legitimate product or service.
- Revenue Source
Legitimate businesses derive their revenue from the sale of products or services. while in a pyramid scheme, revenue comes primarily from recruitment fees or payments made by new members.
- Recruitment vs. Sales
Participants are incentivized to recruit new members to earn money in a pyramid scheme. In contrast, legitimate businesses may offer incentives for sales but primarily focus on selling products or services to generate revenue.
- Sustainability
Legitimate businesses can sustain themselves by continuously selling products or services. Pyramid schemes are inherently unsustainable, as they rely on recruitment to generate returns for existing members, eventually leading to a collapse when recruitment slows down.
- Transparency and Compliance
Legitimate businesses are transparent about their products, services, and business practices. They comply with legal and regulatory requirements. Pyramid schemes often operate covertly and may use deceptive tactics to recruit members.
- Legal Status
Pyramid schemes are illegal in many countries, including the United States, and are considered fraudulent schemes. Legitimate businesses operate within the boundaries of the law and adhere to regulations governing their industry.
By understanding these key differences, individuals can make informed decisions and avoid falling prey to pyramid schemes. It’s essential to conduct thorough research and due diligence before investing in any business opportunity to ensure its legitimacy.
Conclusion
In this blog, hope you find the answer to “Is Senior Life Insurance Company a pyramid scheme?” Senior Life Insurance Company is a legitimate insurance provider, not a pyramid scheme. The company operates within the boundaries of the insurance industry, selling life insurance policies to seniors to help them cover final expenses. It’s important to differentiate between pyramid schemes and legitimate businesses, and Senior Life Insurance Company falls into the latter category.
Suppose you’re considering purchasing a life insurance policy from Senior Life Insurance Company or any other provider. In that case, it’s always a good idea to do your research and understand the terms and conditions of the policy before making a decision.
FAQS
Senior Life Insurance Company is a legitimate, legally licensed life insurance carrier founded in 2000. It is not a pyramid scheme because it sells real insurance products (primarily final expense and burial policies) to actual retail customers. However, it uses a multi-level recruitment model that often faces criticism.
Agents earn money primarily through personal production (commissions from selling insurance policies) and overrides (earning a percentage of sales made by agents they recruit into their “downline”). While you can focus solely on selling, the company’s structure heavily incentivizes building an agency through recruitment.
There is no direct “fee” to join, but it operates on a “pay-to-play” independent contractor model. Agents must cover their own licensing costs, errors and omissions (E&O) insurance, and most notably, they must purchase their own leads from the company to find clients, which can become expensive.
The main criticism is its heavy emphasis on continuous recruiting and the MLM-style hierarchy. Some former agents express frustration over the high cost of leads relative to conversion rates, and the fact that uplines profit off the recruits’ production, making it feel like a recruitment-first environment to outsiders.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.