
Buying whole life insurance because an agent said it “builds wealth,” or buying term life insurance without checking what happens after it expires, are two of the most expensive mistakes a policyholder can make. Both decisions can leave a family underinsured or overpaying for decades, and neither mistake becomes obvious until it is too late to fix cheaply.
Quick Answer: Term vs Whole Life Insurance Pros and Cons
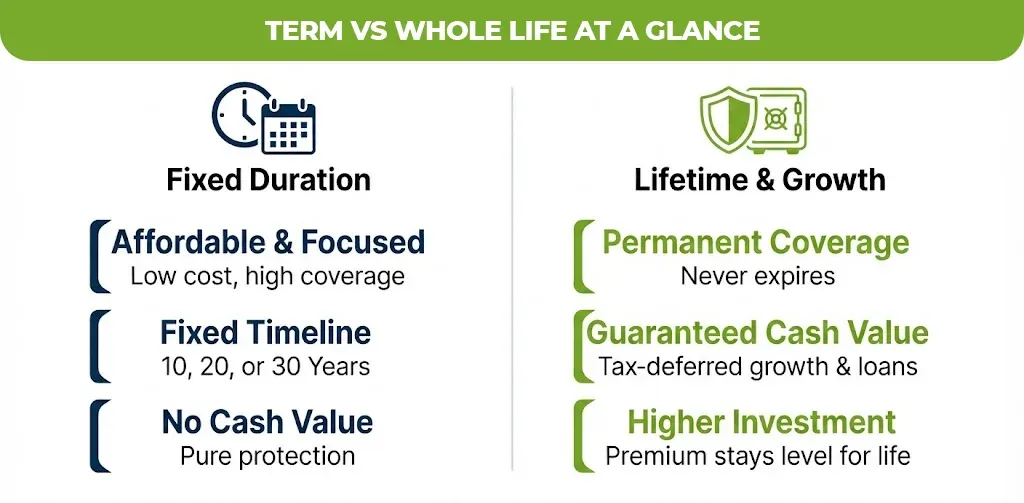
Term life insurance offers lower premiums and coverage for the fixed time that is generally 10, 20 or 30 years but it builds no cash value and it ends with no payout if you outlive the term. Whole life insurance cost more but it covers you for your entire life and also builds guaranteed cash value that you can borrow against later.
Term vs Whole Life Insurance Pros and Cons at a Glance
The fastest way to see the difference is side by side. Term life insurance wins on affordability and simplicity, while whole life insurance wins on permanence and guaranteed cash value.
| Factor | Term Life Insurance | Whole Life Insurance |
| Coverage length | Fixed term, usually 10 to 30 years | Entire lifetime, as long as premiums are paid |
| Premium cost | Lower, level for the term | Higher, level for life |
| Cash value | None | Builds guaranteed cash value over time |
| Death benefit | Paid only if death occurs during the term | Paid whenever death occurs, as long as the policy is active |
| Best suited for | Temporary needs like mortgage protection or income replacement | Permanent needs like final expenses or estate planning |
| Flexibility to borrow against policy | Not available | Available through policy loans against cash value |
| Renewal after term ends | Possible but at a much higher premium, or requires new underwriting | Not applicable, coverage does not expire |
What Is Term Life Insurance? Pros and Cons
Term life insurance is a life insurance policy that pays a death benefit only if the insured person dies within the set time that is known as term. Once the term ends, the coverage will stop unless the policy will renew it or converted to the permanent policy. Usually that is done at the significantly higher premium that is based on their age at that time.
Pros of term life insurance
- Premiums are substantially lower as compared to whole life insurance for the same death benefit that will make a larger coverage amount affordable for most budgets.
- The application and underwriting process is generally simpler and faster than for permanent policies.
- It matches coverage to a specific financial obligation, such as a 30-year mortgage or the years until retirement savings are sufficient.
Cons of term life insurance
- The coverage will end when the term expires, and outliving the policy means that the premium paid does not return any value.
- Renewing after the term often costs far more, since pricing is based on your age and health at renewal, not your original age.
- It builds no cash value, so there is no savings or borrowing component built into the policy.
What Is Whole Life Insurance? Pros and Cons
Whole Life insurance is a type of permanent life insurance policy that covers the policy holders for their entire life as long as they are paying premiums on time. Part of each premium payment goes towards the death benefit and part builds a cash value account that will grow on a tax deferred basis.
Pros of whole life insurance
- Coverage never expires, so the death benefit is guaranteed to pay out eventually, regardless of when death occurs.
- The cash value component grows at a guaranteed minimum rate set by the insurance company, and the policyholder can borrow against it while still alive.
- Premiums are typically level for life and do not increase with age or new health issues, unlike renewing a term policy later.
Cons of whole life insurance
- Premiums cost significantly more than term life insurance for an equivalent death benefit, which strains monthly budgets for many households.
- Cash value growth in the early policy years is usually modest, since a larger share of early premiums covers the cost of insurance and administrative fees.
- The complexity of riders, dividends, and loan provisions makes it harder to compare policies across insurance companies without professional guidance.
Term vs Whole Life Insurance Cost Comparison
Whole life insurance premiums for the same death benefit is generally higher as compared to term life insurance at the same age. This is because the whole life guarantee pay out and through the receiving component that term life insurance does not. Based on the published 2026 rate data that is compiled by ConsumerAffairs, a healthy 30 year old male paying for a 20-year, $250,000 term policy pays roughly $24.57 per month, compared to roughly $139.48 per month for a whole life policy with the same $250,000 death benefit.
| Policy Type | Coverage Amount | Approximate Monthly Premium (30-year-old male, good health) |
| 20-year term life | $250,000 | $24.57 |
| Whole life | $250,000 | $139.48 |
| Whole life | $100,000 | $71.55 |
all these figures can be changed by insurance company, health class, gender and state. So treat them as the starting reference rather than a personal quote.
Most of the people misjudge this cost gap before they ever get a quote. According to the 2025 Insurance Barometer Study conducted jointly by LIMRA and Life Happens, healthy young adults between 18 and 30 overestimate the median cost of a $250,000, 20-year term policy by 10 to 12 times its true price, and historically about three-quarters of American adults overestimate life insurance costs in general.
When Term Life Insurance Makes More Sense
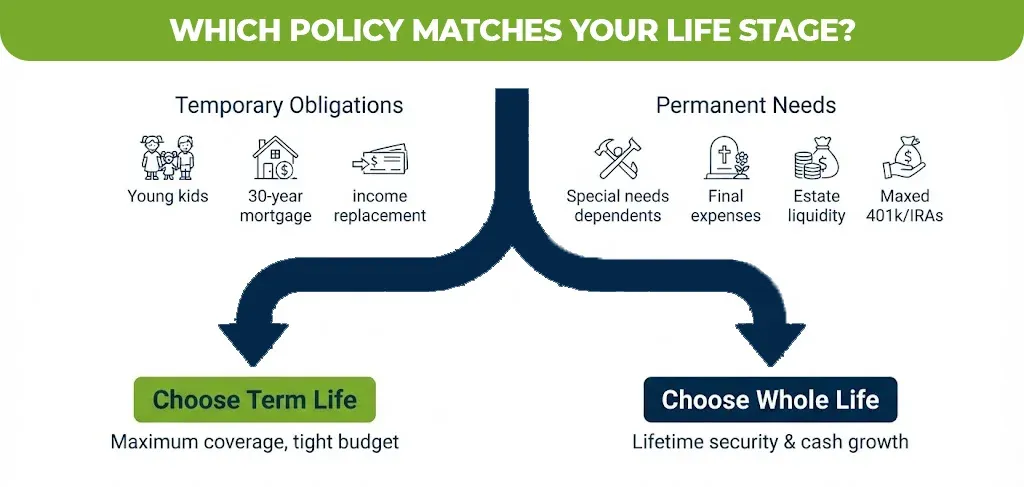
Term Life insurance makes sense when you need for coverage has a clear end date. A 30-year-old with a 30 year mortgage and two young children has a financial obligation that shrinks overtime since the mortgage drops and the children eventually become financially independent.
Term life insurance also fits people who are early in their career and need maximum coverage on a limited budget, since the lower premium allows for a larger death benefit than the same budget would buy in whole life insurance.
When Whole Life Insurance Makes More Sense
Whole life insurance makes sense when the need for coverage has no end date. Final expense planning, permanent care for dependents with special needs and estate liquidity for the largest estates are all that needs that do not disappear after 20 or 30 years.
Whole life insurance also appeals to people who have already maxed out other tax-advantaged savings vehicles such as 401 K, IRA or HSA want an additional vehicle with guaranteed, tax advantage cash value growth. This is an error use case then the general population says the higher premium only makes the financial sense once the other retirement saving priorities are already funded.
How Underwriting and Insurer Ratings Affect Your Decision
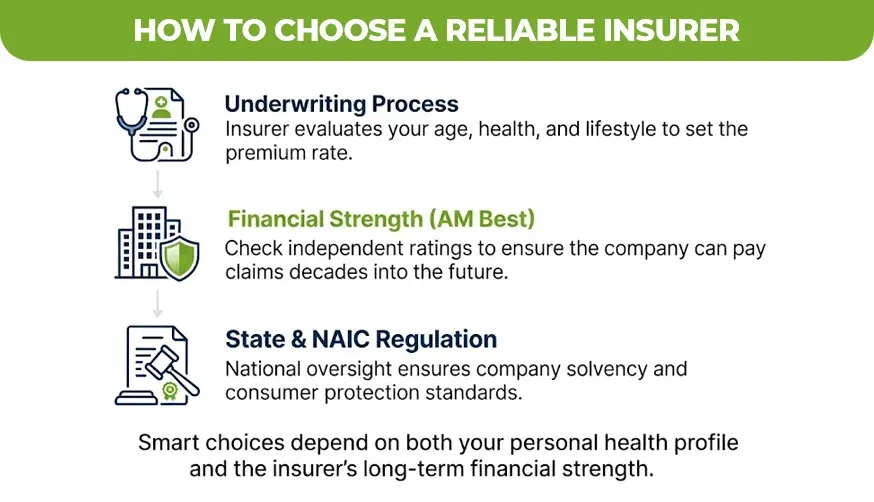
Every life insurance application goes through underwriting, the process an insurance company uses to evaluate your health, age, lifestyle and risk profile before setting your premium. According to a 2025 insurance barometer study, less than a 9:45 adults and millennials say that they understand the underwriting process which contribute to hesitation and cost confusion when shopping for the coverage as reported by Life Happens.
Before choosing an insurance company for either term or whole life insurance, you have to check the company’s financial strength rating from an independent rating agency such as AM best. Since this rating reflects the insurance companies ability to pay the claims decades into the future.
State insurance regulation, coordinated nationally through the National Association of Insurance Commissioners (NAIC), also requires insurers to meet solvency and consumer protection standards, which adds a layer of oversight beyond the individual policy contract.
Term vs Whole Life Insurance: Which One Should You Choose?
Choose term life insurance if your primary goal is replacing income or covering a debt for a specific number of years at the lowest possible cost. Choose whole life insurance if your primary goal is guaranteed lifetime coverage, a permanent death benefit, or a cash value savings component you can access while alive.
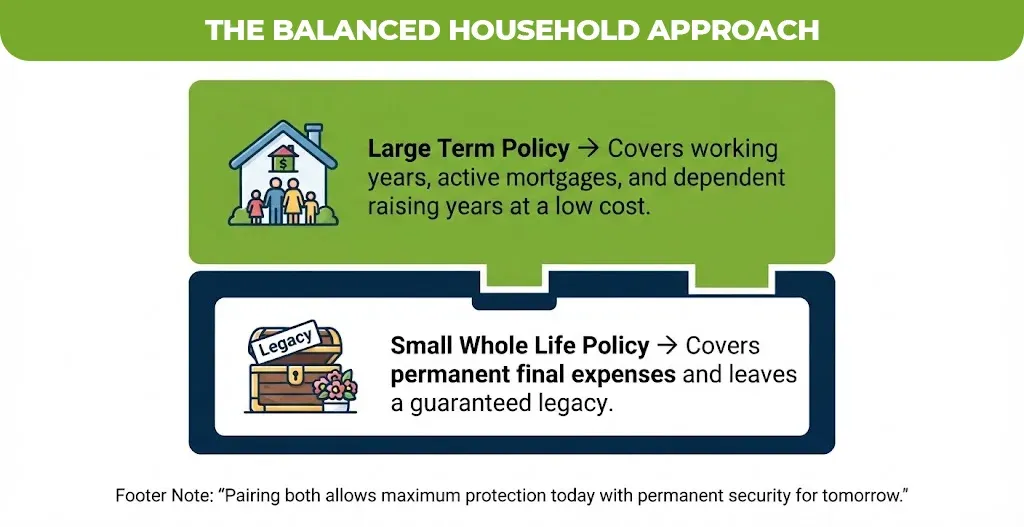
Many households use both. A common approach pairs a large term policy to cover the working years and major debts with a smaller whole life policy sized to cover final expenses and leave a guaranteed, permanent benefit to beneficiaries.
Talk to Someone Before You Decide
Comparing term vs whole life insurance pros and cons on paper use so far since the right answer totally depends on your income, dependent, existing savings and how long you actually need the coverage to last. M-life insurance can walk you through your specific situation and show you the real quotes for both policy types side-by-side so that you are choosing based on your numbers rather than a generic rule of thumb. If you want a second option before signing anything, reaching out costs nothing and there is no obligation to buy.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.