
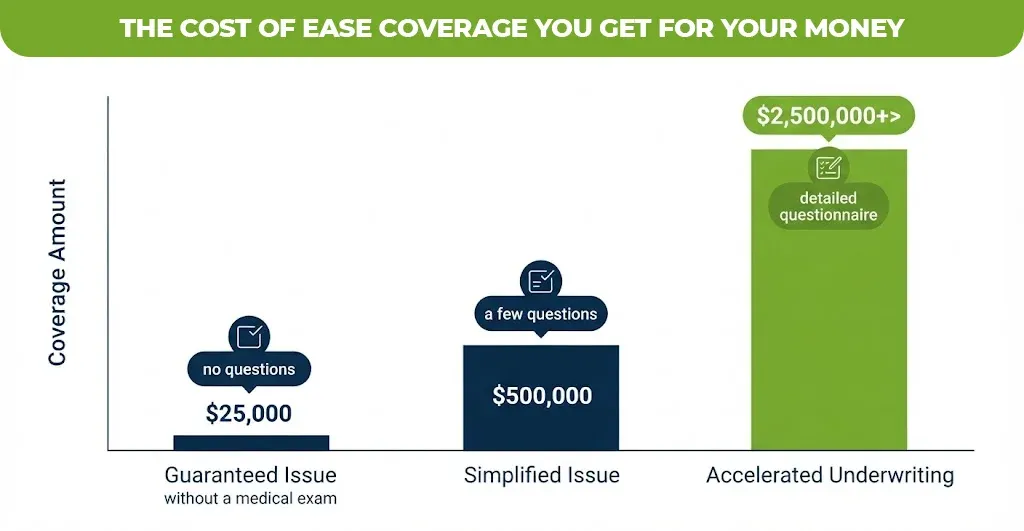
The expensive mistake is buying the first “no health questions, guaranteed acceptance” policy you see in an ad. Those policies cap out around $25,000 and usually pay nothing but your premiums back if you die of natural causes in the first two years. If you are healthy enough to answer a short questionnaire, you were probably eligible for a $500,000 policy at a fraction of the cost per dollar of coverage, approved in minutes.
Life insurance without medical exam is now mainstream, not a last resort. The question is not whether you can skip the needle. It is which of the three no-exam paths you actually qualify for.
Quick Answer
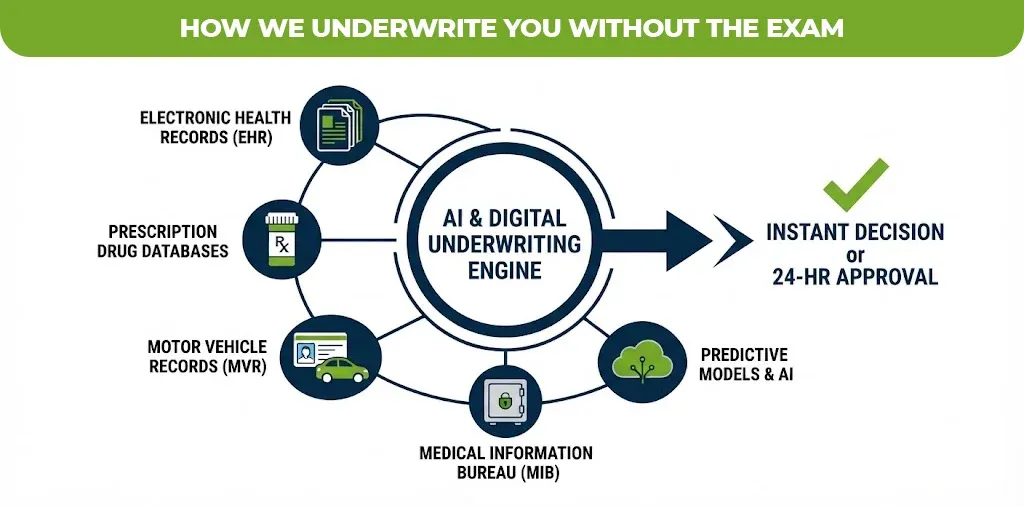
Yes, you can get life insurance without a medical exam in 2026. There are three routes. Accelerated underwriting gives healthy applicants full-size term coverage, often $1 million or more, at rates close to fully underwritten policies. Simplified issue asks 5 to 15 health questions and typically caps coverage near $500,000. Guaranteed issue asks nothing at all but limits coverage to roughly $5,000 to $25,000 and applies a two-year graded death benefit. Apply for the best one you can qualify for, not the easiest one to get.
Can you get life insurance without a medical exam, and is it legitimate?
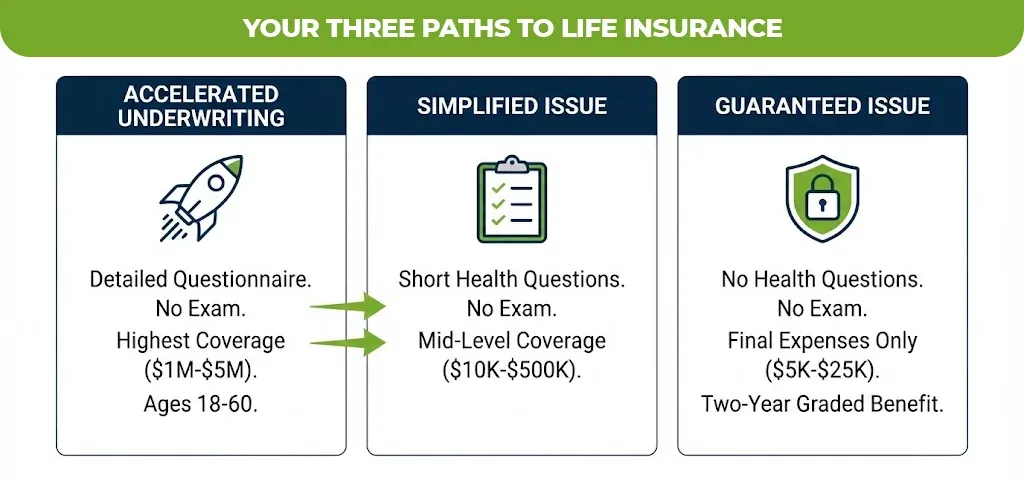
Yes. Instead of blood and urine samples, insurers verify risk using prescription drug databases, Medical Information Bureau records, motor vehicle records, electronic health records and predictive models. This is a regulated process, not a loophole. The National Association of Insurance Commissioners oversees insurers’ use of external data, predictive models and AI in underwriting through several working groups, including work following its Model Bulletin on the Use of Artificial Intelligence Systems by Insurers (NAIC, Accelerated Underwriting). NAIC
Coverage limits have climbed sharply. Industry analysis of 2026 programs notes that some carriers now approve face amounts as high as $5 million without a traditional medical exam, relying on electronic health records, prescription databases and behavioral data (actuary.info, 2026). Actuary
Key Takeaways
- A life insurance policy without a medical exam still involves underwriting. Only guaranteed issues skip health screening entirely.
- Answering more questions almost always buys you more coverage for less money.
- Guaranteed issue is a final expense product, not income replacement.
- Price misperception is the real barrier. In the 2026 Insurance Barometer Study from LIMRA and Life Happens, 40% of Americans overestimated the cost of a basic 20-year term policy, and about 48% said their estimate was a gut feeling or wild guess (InsuranceNewsNet, April 2026). InsuranceNewsNet
What are the three types of life insurance policies without a medical exam?
Each path trades approval speed for coverage size and price.
| Feature | Accelerated underwriting | Simplified issue | Guaranteed issue |
| Health questions | Detailed questionnaire | Short list of yes/no questions | None |
| Medical exam | No | No | No |
| Typical coverage | $1M to $3M, some to $5M | $10,000 to $500,000 | $5,000 to $25,000 |
| Typical age range | 18 to 60 | Varies by carrier | About 45 to 85 |
| Waiting period | None | Usually none | Two years, graded |
| Product type | Mostly term life | Term or whole life | Whole life only |
| Decision time | Minutes to 48 hours | Same day to days | Immediate |
Accelerated underwriting is the route behind most term life insurance without a medical exam sold online today. Lincoln Financial’s TermAccel program, for example, offers instant-decision coverage up to $2.5 million for ages 18 to 60 (Penny Pincher, March 2026). Penny Pincher
One caveat worth knowing before you apply: applying for a no-exam product does not guarantee the exam is waived. If you request a very high face amount or your answers conflict with prescription and database records, the insurer can move your file to full underwriting.
What does cheap life insurance without a medical exam cost in 2026?
Term pricing is the anchor. The figures below are market averages for $500,000 of 20-year term coverage for nonsmokers, published in the Policygenius Life Insurance Price Index.
| Profile | Monthly premium |
| Woman, age 30, preferred | $23.10 |
| Man, age 30, preferred | $29.56 |
| Woman, average across ages | $47 |
| Man, average across ages | $59 |
The first two rows reflected polygenius price index average is as of October 2025 for a healthy unspoken 30 year old. The blended averages come from the money geeks 2026 analysis that put a $500,000.20 year term life insurance policy add $47 per month for and $59 per month for month.(MoneyGeek, August 2026).
Permanent coverage costs far more for the same death benefit. A $500,000 whole life policy runs roughly 9 to 10 times a comparable 20-year term policy, with a healthy 40-year-old woman paying about $451 per month versus $47 for term. That gap is why affordable whole life insurance without medical exam usually means a small final expense face amount, not a half-million-dollar policy. MoneyGeek
Expect a modest premium bump for skipping the exam on term coverage. Because underwriters price conservatively without lab results, no-exam premiums often sit somewhat above fully underwritten equivalents, though the gap narrows for healthy applicants using accelerated underwriting.
Life insurance for seniors without medical exam: what changes after 60
Options narrow, and the graded benefit becomes the central issue. Many insurers offer guaranteed issue whole life for ages 50 to 85 with no exam and no health questions, with coverage limited to roughly $5,000 to $30,000 and a two-year waiting period before full benefits are payable (MoneyGeek).
Here is what “graded” means in practice. With Corebridge Direct’s guaranteed issue product, a natural death in the first two years pays 110% to 120% of premiums paid, while accidental death pays the full face amount, and after two years the full face amount applies (Corebridge Direct).
Simplified issue sits between the two and is usually the better senior buy when health allows it. USAA, for instance, offers guaranteed acceptance coverage up to $25,000 for ages 45 to 85, holds an A++ AM Best rating and carries an NAIC complaint index of 0.12 against a 1.00 industry average. MoneyGeek
A realistic scenario
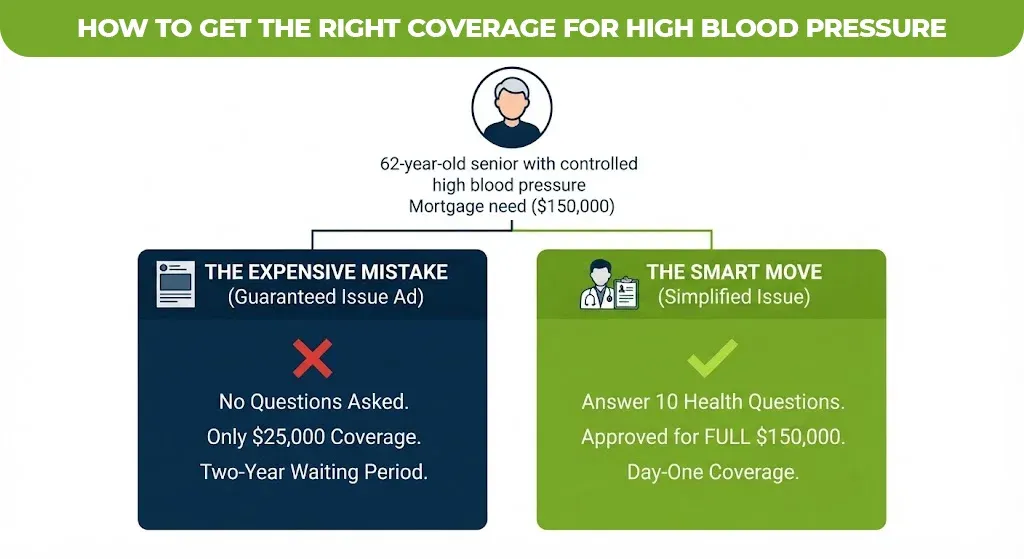
Consider a 62-year-old with controlled high blood pressure and a statin prescription who wants $150,000 to clear a mortgage. A guaranteed acceptance ad would sell her a $25,000 policy with a two-year wait. A simplified issue application asking ten health questions could approve the full $150,000 with day-one coverage, because managed hypertension is an insurable condition at most carriers. The difference is not luck. It is applying one tier up.
How do you compare the best life insurance companies without a medical exam?
Price alone is a weak filter. Check four things before you sign.
- Financial strength. AM Best ratings measure an insurer’s ability to pay claims decades from now.
- Complaint history. The NAIC Consumer Information Source publishes complaint indexes by company at naic.org. Below 1.00 means fewer complaints than expected for the company’s size.
- The graded benefit language. If the illustration mentions a return of premium in years one and two, you are buying a guaranteed issue.
- The free look period. State law gives you a window, commonly 10 to 30 days, to cancel for a full refund after the policy arrives.
Also compare at least three carriers. Underwriting rules differ enough that the same health history can produce a graded offer at one company and full day-one approval at another.
How to get life insurance without medical exam without overpaying
Work top down rather than bottom up.
Start with accelerated underwriting term quotes if you are under 60 and reasonably healthy. Drop to simplified issue only if you are declined or your condition is outside the carrier’s appetite. Treat guaranteed issue as the floor, chosen when health rules everything else out.
Be accurate on the questionnaire. Underwriters still review your medical history, and information that contradicts your answers can lead to a declined application or a denied claim after your death (U.S. News). U.S. News & World Report
Finally, name and update your beneficiaries. A death benefit generally passes to beneficiaries income tax free, but an outdated designation can send it to the wrong person.
Next step
You do not need to pick a policy today. You do need to know which underwriting tier you fall into, because that single fact decides your price and whether your family waits two years for the full benefit.
If you want that checked against multiple carriers before you apply, M Life Insurance can run side by side quotes for no-exam term, simplified issue and guaranteed issue so you can see the real numbers for your age and health profile. No exam, no pressure, just a clear comparison.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.