
Waiting for the “perfect time” to buy life insurance is the most expensive mistake people make with this decision. Premiums rise every year you wait, health changes can disqualify you from the best rates, and a sudden diagnosis can shut the door on coverage entirely. The right time to get life insurance is almost always earlier than people think, and the data backs this up directly.
Nearly 4 in 10 insured consumers wish they had purchased their policies at a younger age. (limra.com) That regret is almost always tied to cost, health, or a life event they didn’t plan around. This guide walks through exactly when to get life insurance, what determines the right time for your situation, and how to avoid becoming another statistic in that regret column.
Quick Answer
The best time to get life insurance is as soon as you can have any one financially dependent on you. No matter if that is a spouse, a child, business partner or aging parents. Age and health are the two biggest factors in your premium. So buying while you are young and healthy looks in lower rates for the life of the policy. If you are waiting for the milestone like marriage or mortgage, note that many people already need coverage before those events happen particularly if they carry debt or support anyone else financially.
When Do You Actually Need to Get Life Insurance?
You need life insurance for the moment someone else depends on your income or would be financially burdened by your death. This is not a specific birthday. It is tied to financial dependence, debt and future obligations.
The common triggers include having a child, taking on a mortgage or major loan, getting married, starting a business with a new partner or becoming the primary income owner in your household. Even adults without dependence often carry a real need if they have cosign that, aging parents who rely on them, or outstanding student loans that would pass to a co-signer.
This is where, when is a good time to get life insurance, get misunderstood. People wait for one obvious signal like a wedding when the real signal is usually smarter and earlier such as taking on a car loan with the cosigner or moving in with a partner who share rent and bills.
Is It Better to Get Life Insurance When You’re Young?
Yes, buying life insurance at a younger age locks in lower premiums and reduces the risk of being denied coverage due to a future health change. This is the single clearest financial argument for not waiting.
Life insurance pricing is based heavily on age and your health time when you apply. The applicant in their 20s or early 30s will consistently qualify for the lower rates as compared to the same person applying ten years later. Even if nothing else about their health changes. Once a new diagnosis, it can be a diabetes, high blood pressure or something more serious enters the picture the options are narrow and cost can climb.
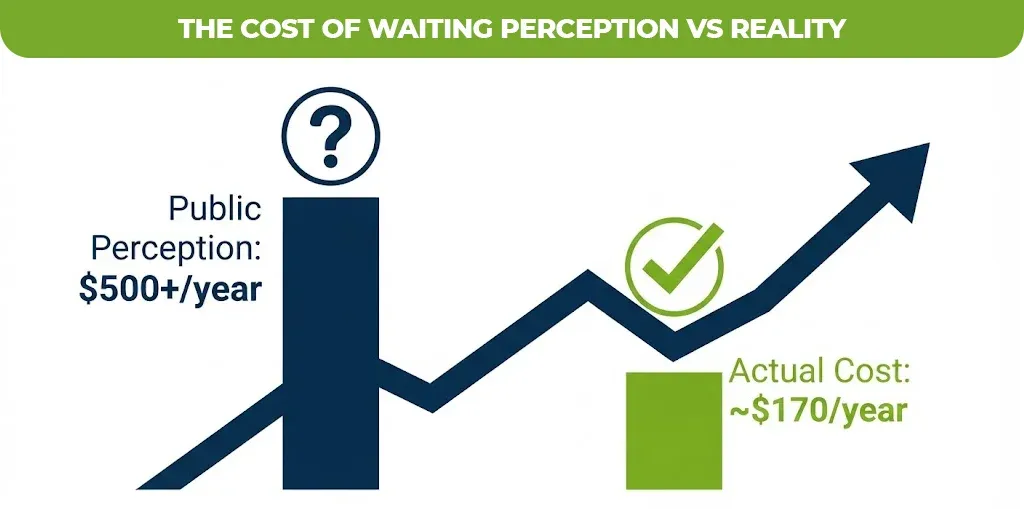
The data on this misconception is striking. Respondents in LIMRA’s Insurance Barometer Study are consistently asked to estimate the cost of a $250,000, 20-year term policy for a healthy 30-year-old, and for years, more than half have guessed the price at three times the real cost or higher.In a 2022 LIMRA survey, more than half of respondents estimated the cost of a $250,000, 20-year term life insurance policy for a healthy 30-year-old male at $500 per year or more, while the average actual cost is closer to $170 per year. (blog.massmutual.com) That single misconception keeps a lot of young, healthy people from locking in the cheapest coverage they will ever qualify for.
When Is the Best Age to Get Life Insurance?
There is no single best age, but the data shows the cost advantage of buying earlier is significant and compounds the longer you wait. The most efficient window is generally your twenties through mid-thirties, when premiums are at their lowest and health status is typically strongest.
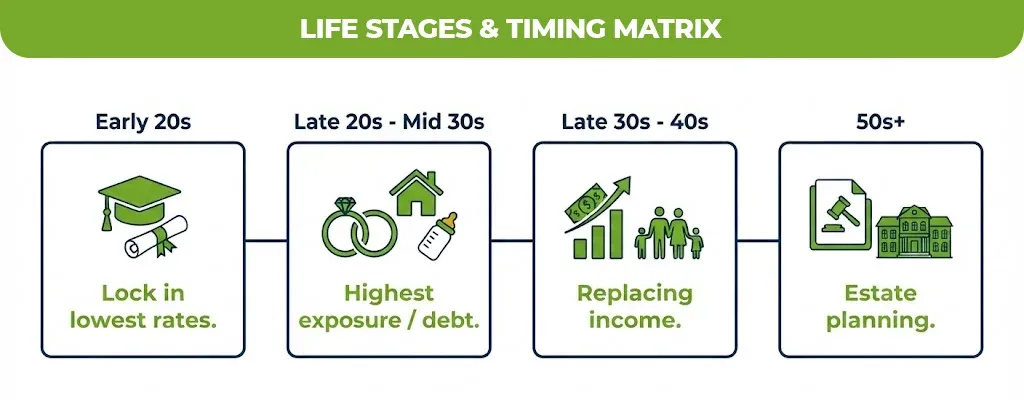
That said, “best age” depends on when your financial responsibilities start. Someone who becomes a parent at 25 has a different urgency than someone who remains child-free and debt-free until their late thirties. The table below shows how the underlying logic changes by life stage rather than by a fixed number.
| Life Stage | Typical Trigger for Coverage | Why Timing Matters |
| Early 20s, single, no dependents | Student loans with a cosigner, or supporting a parent | Locks in the lowest possible premium for decades |
| Late 20s to mid 30s, married or partnered | Shared debt, mortgage, or a first child | Highest financial exposure if income stops suddenly |
| Late 30s to 40s, established career | Higher income to replace, growing family expenses | Premiums rise with age, so delay increases lifetime cost |
| 50s and beyond | Estate planning, final expenses, remaining dependents | Fewer term options may be available, permanent policies become more relevant |
When to Get Term Life Insurance vs Whole Life Insurance
Term life insurance is generally the right starting point for everyone who needs affordable coverage that is guided to a specific time such as the years until a mortgage is paid off or children become financially independent. Whole life insurance and other forms of permanent life insurance fits differently since they are designed to last for your entire life and also build cash value over time.
The decision between when to get term life insurance and when to get whole life insurance or universal life insurance comes down to purpose and budget. Term life insurance policies typically carry lower premiums for the same death benefit, which makes them the more common choice for young families focused on income replacement. Permanent life insurance, including whole life insurance and universal life insurance, costs more but adds a savings or investment component and does not expire as long as premiums are paid.
There are some buyers who also ask about supplemental life insurance. Which is coverage added on the top of an employer provided policy or an individual policy. And it is often to close a gap when workplace coverage alone would not replace enough income.
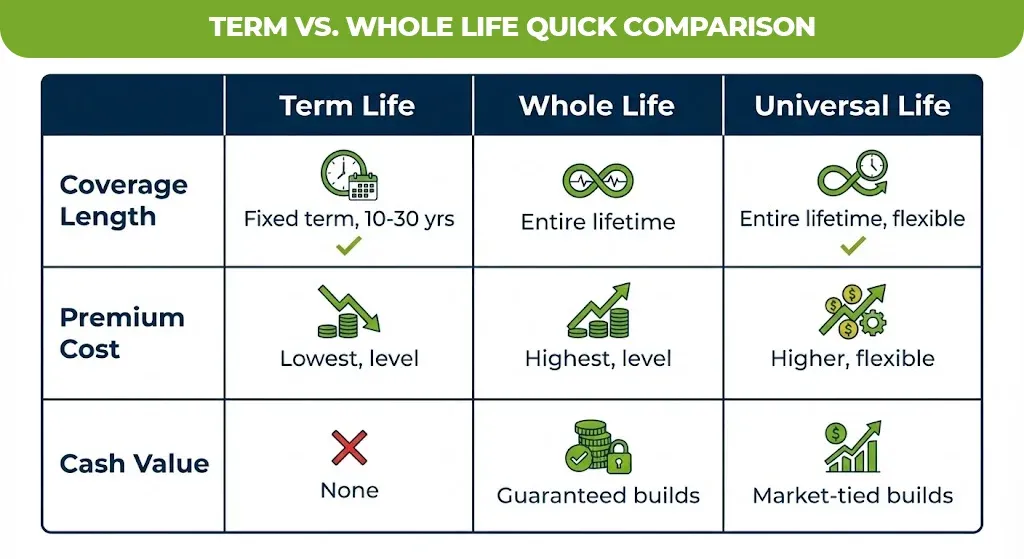
| Factor | Term Life Insurance | Whole Life Insurance | Universal Life Insurance |
| Coverage length | Fixed term, commonly 10 to 30 years | Entire lifetime | Entire lifetime, with flexible terms |
| Premium cost | Lowest for the same death benefit | Higher, level premiums | Higher, but often flexible |
| Cash value | None | Builds guaranteed cash value | Builds cash value, often tied to market performance |
| Best for | Income replacement during working years and debt payoff | Lifelong coverage, estate planning, final expenses | Lifelong coverage with more premium flexibility |
Is It Ever Too Late to Get Life Insurance?
It is rarely too late to get some form of life insurance but the options there and the cost rise the longer you wait, particularly after a serious health diagnosis. Most of the insurance companies still offer coverage well into a person’s 60s and 70s, although term length shortens and permanent policies or final expense insurance often become the more realistic path.
Underwriting is the process that insurance companies used to assess your health, age and risk before setting your premium and approving coverage at all. The further you are from your healthiest years when you apply, the more underwriting can work against you. Which is exactly why financial professionals consistently recommend applying for a health issue forces the decision rather than after.
What Happens If You Wait Too Long to Get Life Insurance?
Waiting too long generally means paying more of the same coverage or in some cases being declined altogether due to a new health condition. It can also mean your dependents are left financially exposed during the exact years you were planning to protect them.
This is where beneficiaries and the death benefit come into focus. A death benefit is the amount your insurance company pays to your named beneficiaries when you pass away, and it is only available if a policy is active at the time of death. A gap in coverage, even a short one caused by delay, means that protection simply does not exist for your family during that window.
The financial impact of that gap is not abstract. According to the 2025 Insurance Barometer Study, one and four adult Americans say that their household would feel the financial impact of losing the primary wage owner within one month or less. One in four adult Americans say their household would feel the financial impact of the death of the Prime wage owner in one month or less according to the 2025 Insurance Barometer Study from Life Happens and LIMRA. (lifehappens.org) That is the real cost of waiting, measured in weeks rather than years.
How to Choose the Right Life Insurance Policy Once You Decide to Buy
Once you know it is time to get a life insurance policy, the next decision is choosing the right type and amount. Start with coverage amount, which is typically based on income replacement, outstanding debt, and future obligations like college costs.
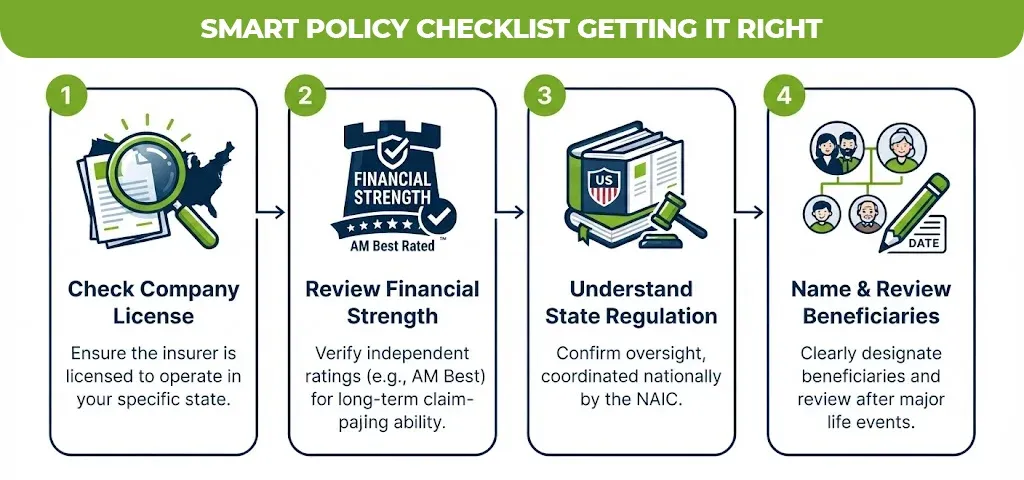
Check that any company you are considering is licensed in your state and review its financial strength rating from an independent agency such as AM best. This reflects the insurance companies ability to pay the claims over the long-term. It is also worth confirming how the policies regulated since life insurance in the United States is overseen at the state level, coordinated nationally through the national Association of insurance commissioners RNIC which sets the model standard that most states adopted.
Finally, name your beneficiaries clearly and review them after major life events like marriage, divorce, or the birth of a child. An outdated beneficiary designation is one of the most common and avoidable problems families run into after a claim.
Figuring out the right coverage amount and policy type is easier with a second set of eyes on your specific situation. MLife Insurance can walk you through your options and help you see what coverage would actually cost at your age and health profile, with no pressure to decide on the spot.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.