
If you die or become permanently unable to work, your business does not pause. Payroll still runs, loans still come due, and a partner may suddenly own a stake they never wanted to manage alone. Without the right life insurance for business owners in place, that gap gets paid for out of the company’s cash flow, or it does not get paid at all.
This is not the same as personal life insurance. Life insurance for small business owners has to answer questions personal policies never touch, that is who inherits your ownership stake, who repays a business loan, and who buys out your share so a surviving partner is not stuck running a company with your family. Getting this wrong is one of the most common and most expensive planning mistakes business owners make.
Quick Answer: Do Business Owners Need Life Insurance?
Yes, and often more than one policy. A general business life insurance for the owners set up through personal coverage for the owner’s family, personal life insurance that is owned by the business to cover the lost revenue if a critical owner or employee dies, and a buy sell agreement that is funded by the life insurance so that the surviving partner can buy out a deceased owner’s share without a fire sale. Lenders can also require coverage before approving a loan.
Key Takeaways
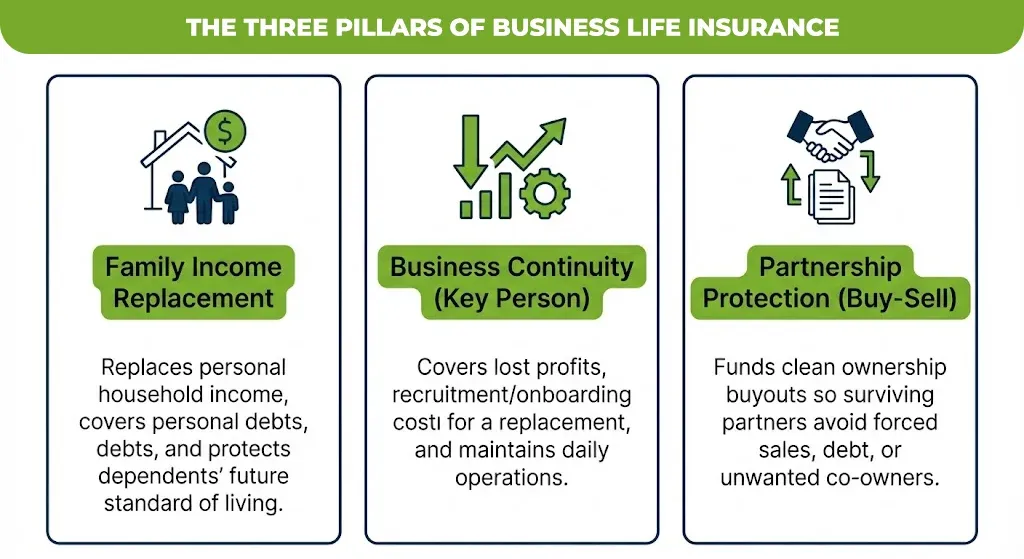
- Generally life insurance for business owners serves three separate purposes and these are family income replacement, business continuity, and loan or partnership protection.
- Nearly half of the small business owners expect to retire within the next decade, yet a Chase survey from May 2026 found that only a small share have a fully developed succession plan, according to JPMorganChase.
- Premiums paid by a business are generally not tax-deductible when the business is directly or indirectly the beneficiary of the policy, under IRC Section 264 and 26 CFR § 1.264-1.
- The first $50,000 of employer-provided group-term life insurance is excluded from an employee’s taxable income under IRC Section 79.
- SBA loans over $350,000 that are not fully secured by other collateral typically require life insurance on the principal owners.
Life Insurance for Business Owners Definition: Why It Is Different From Personal Coverage
Life insurance for business owners is coverage structured around business risk, not just family income replacement. The policy owner, the beneficiary, and the purpose of the death benefit all change depending on what the policy is protecting.
A personal policy protects your household. A business policy protects the company’s ability to keep operating, repay debt, or transfer ownership cleanly. Confusing the two is how families end up owning a policy meant to fund a buyout, or a business ends up owning a policy meant to support a spouse.
Three entities show up again and again in this planning and these are the insured that is the owner or key employee, the policy owner (the individual or the business), and the beneficiary (the one who receives the death benefit). Getting all these three roles right at setup avoids costly restructuring later.
Key Person Life Insurance: Protecting the Business Itself
Key person life insurance is sometimes also called key man insurance and this is a life insurance policy that a business buys for an important owner, founder or employee. The business pay the premiums and receives the money if that person dies. The money can help the business to handle lost income, hiring cost or other financial problems. The business is the beneficiary, not the employees family.
The death benefit covers what actually breaks when that person is gone: lost gross profit while a replacement is found, recruiting and onboarding costs, and continued debt payments. Key person life insurance for small business owners is especially common in businesses built around one or two people’s relationships, expertise, or licenses.
Lender’s frequently required coverage as a loan condition. SBA guidance under its standard operating procedure generally calls for the life insurance on the principles of sole proprietorship, single member LLCs or business that depend heavily on owners active participation, generally for the loan above $350,000 that are fully not secured by other collateral.
Buy-Sell Agreements and Life Insurance for Business Owners to Protect Partners
A buy-sell agreement is a legal contract that will determine what happens to an owner’s share of business if they die, if they become disabled or want to exit. Life insurance is the most common way to fund that agreement because the death benefit provides cash exactly when it is needed without forcing a sale of business assets.
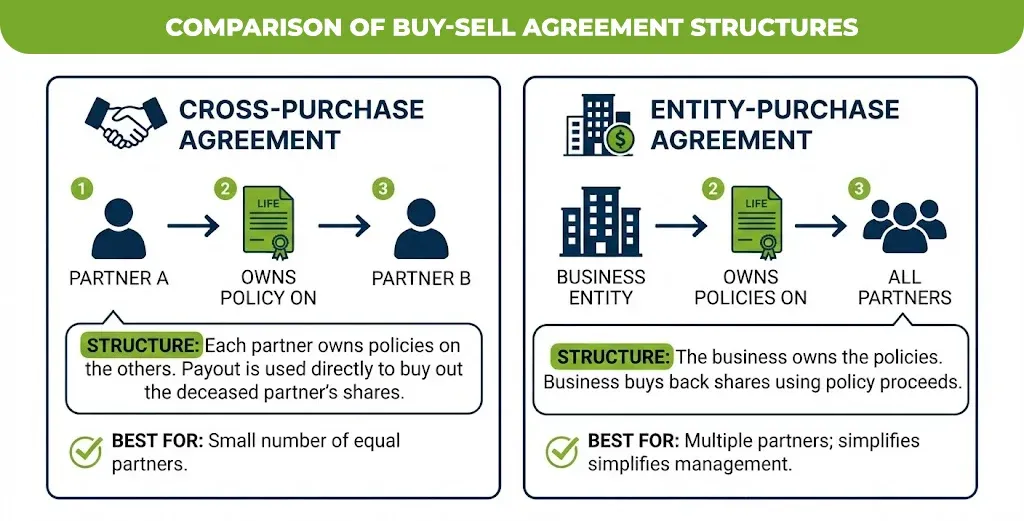
There are two common structures. In a cross-purchase agreement, each partner owns and is the beneficiary of a policy on every other partner, and uses the payout to buy the deceased partner’s shares directly. In an entity-purchase agreement, the business itself owns the policies and buys back the shares using the proceeds.
Life insurance for small business owners to protect partners matters most when there are two or more owners with unequal roles or unequal ability to buy out a departing partner’s stake in cash. Without this funding in place, a surviving partner is often forced to either take on debt or bring in a new, unfamiliar co-owner.
Types of Life Insurance for Business Owners: Term, Whole, Universal, and Cash Value
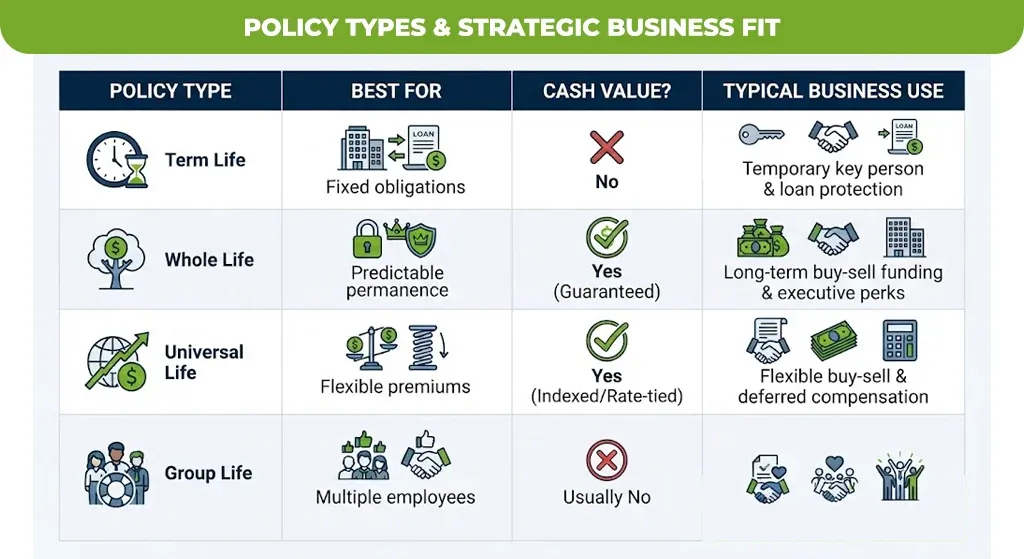
The types of life insurance for business owners generally fall into two categories and these are term life insurance for the business owners which provide coverage for a set time at the lower cost and the permanent policy such as whole life insurance for the business owners and universal life insurance for the business owners which built cash value along side the death benefit.
| Policy type | Best for | Cash value | Typical use in business planning |
| Term life insurance | Covering a fixed obligation, such as a business loan or a set buy-sell term | No | Loan protection, temporary key person coverage |
| Whole life insurance | Owners wanting predictable, permanent coverage | Yes, grows at a guaranteed rate | Long-term buy-sell funding, executive benefits |
| Universal life insurance | Owners wanting flexible premiums and death benefit amounts | Yes, tied to interest rates or an index | Flexible buy-sell funding, deferred compensation |
| Group life insurance | Covering multiple employees at once | Usually no | Employee benefits, baseline key employee coverage |
Cash value life insurance for business owners can serve a secondary purpose beyond the death benefit. Some businesses borrow against a policy’s accumulated cash value for short-term liquidity, though this reduces the death benefit until repaid and should be discussed with a licensed advisor before committing to it as a strategy.
Group Life Insurance for Small Business Owners and Coverage for Key Employees
Group life insurance for small business owners is typically offered as a standard employee benefit, covering all eligible employees, often including the owner, under one master policy. It is inexpensive per person and simple to administer, but coverage amounts are usually modest and tied to salary.
Life insurance for the business owners and key employees often layer group coverage with a separate, higher individual policy on the people who lost would be disproportionately costly, department heads, top sales persons are specialized technical staff. Group coverage protects morale and baseline benefits. Individual key person coverage protects the business’s bottom line.
Under IRC Section 79, the first $50,000 of employer-provided group-term life insurance is excluded from an employee’s taxable income, according to the IRS. Coverage above that amount is subject to imputed income rules, which is worth knowing before designing a benefits package around a high coverage multiple.
Life Insurance Needs for Business Owners: How Much Coverage Is Enough
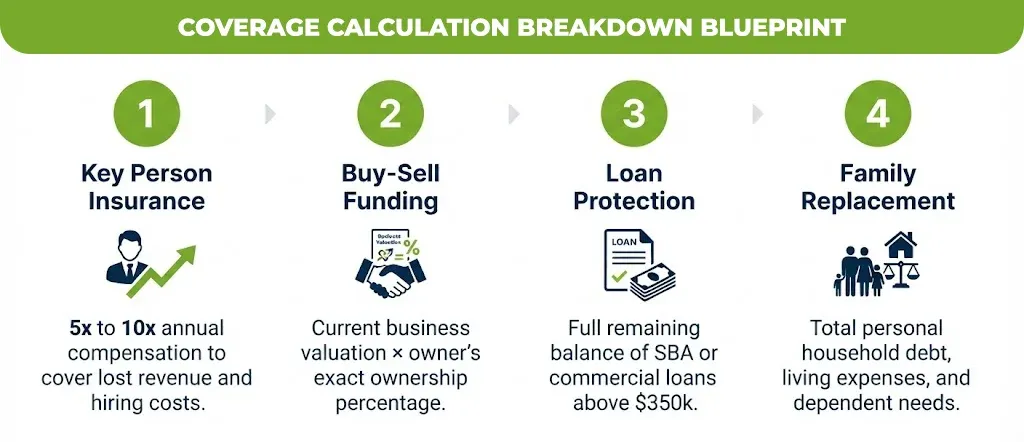
Life insurance needs for business owners are typically calculated separately for each purpose rather than as one combined number. A common approach adds together outstanding business debt, projected replacement costs for a key person, and the buyout value needed to fund a partner’s share under the buy-sell agreement.
| Coverage purpose | What it should cover | Common calculation starting point |
| Key person insurance | Lost revenue and replacement costs | 5 to 10 times the key person’s annual compensation |
| Buy-sell funding | Full buyout value of an owner’s share | Current business valuation multiplied by ownership percentage |
| Loan protection | Outstanding loan balance | Full remaining balance at time of underwriting |
| Family income replacement | Personal household needs | Based on personal income, debts, and dependents |
Commercial Life Insurance for Business Owners: Underwriting and What Affects Approval
Underwriting for the commercial life insurance for business owners looks at both the individual health and business financial standing. The insurance companies generally request financial statements, tax returns and the description of the insured role to confirm the coverage amount matches the actual business risk.
This is different from personal underwriting, where income and health are the primary factors. A business with thin margins or heavy debt may face closer scrutiny, and insurers generally will not approve coverage far beyond what the business’s financials can justify. Working with a broker familiar with commercial life insurance for business owners, rather than a general personal-lines agent, tends to speed this process up.
When comparing insurance companies for business coverage, check each carrier’s financial strength rating from an independent agency such as AM Best, since that rating reflects the insurer’s long-term ability to pay claims decades into the future, not just its current pricing.
Building a Life Insurance Strategy for Business Owners That Actually Holds Up
Start by identifying the single biggest risk to the business if an owner or key person were suddenly gone, then work outward from there. Most businesses find that risk is either loan repayment, loss of a specific relationship or skill set, or an unfunded buy-sell agreement, not all three at once.
Make sure to review coverage whenever the business valuation changes significantly, a new partner joins, or a loan is refinanced. Since the outdated coverage amounts are one of the most common gaps that are found during due diligence or an eventual sale. A life insurance strategy for business owners is not a one-time purchase, it is a plan that needs revisiting as the business grows.
If you are unsure which combination of key person, buy-sell, or group coverage fits your situation, M Life Insurance can walk through your specific ownership structure and loan obligations with you, no pressure, just a clear picture of what actually needs protecting and what does not.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.