
Buying whole life insurance because an agent called it an investment that can also protect your family is one of the most expensive assumptions that you can make. Whole life insurance is specifically paid to pay at each benefit and the cash value growth inside it moves slowly. This especially happened in the first several years of the policy. If you need your money to go fast or you cancel the policy early then you can lose a meaningful part of what you paid in.
Is a whole life insurance policy a good investment? Well for most of the people who are using it purely to build wealth, no. It works better as a long-term, low risk savings and protection tool for people who have already maxed out other retirement accounts, need permanent coverage for the state or business reasons or want a guaranteed piece of their portfolio that will not lose value. The right answer totally depends on your goal, your timeline and also what else you have already saved.
Quick Answer
Whole life insurance is not a good investment if your main goal is growth, since its cash value generally grows at the modest insurance companies declared rate and comes with a life insurance cost that is built into every premium. It can be a reasonable financial tool not purely as investment, for people who want guaranteed, text deferred cash value alongside with the permanent death benefit protection and who also plan to keep the policy for decades. If you are comparing 401K, IRA index fund then those vehicles are generally built for growth. While whole life insurance is built for protection with the saving feature attached to it.
Is Whole Life Insurance a Good Investment? The Direct Answer
Whole life insurance is a good investment only in a narrow set of circumstances, and it is a poor one when compared directly to retirement accounts or index funds for pure growth. The policy’s cash value grows based on a guaranteed minimum rate plus any dividends the insurer declares, not on market performance.
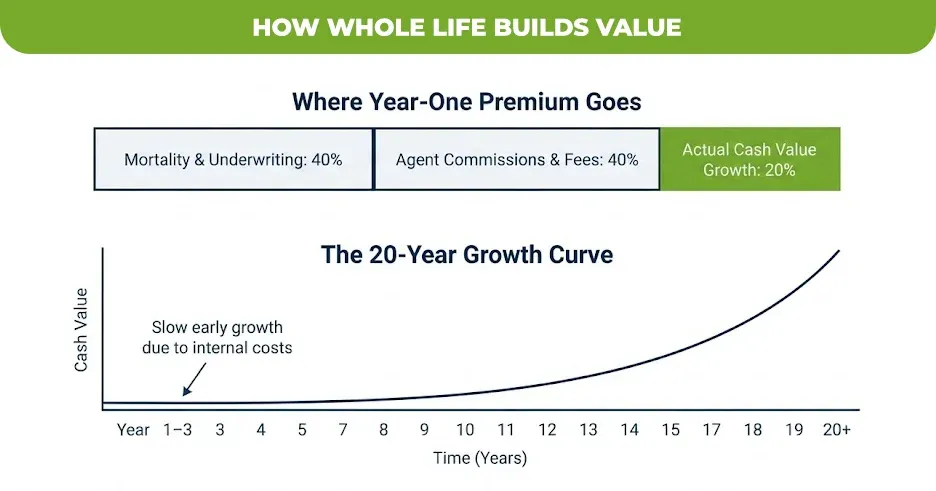
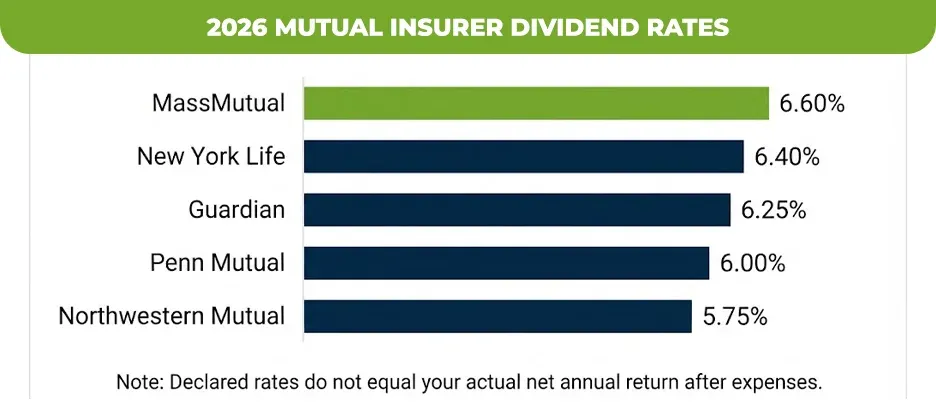
For 2026, the major mutual insurance company declared dividend interest rates between 5.7% and 6.60% depending on the company according to carrier-published rate sheets compiled by Insurance Geek and TopWholeLife.MassMutual leads the field in 2026 at 6.60%, followed by New York Life at 6.40%, Guardian at 6.25%, Penn Mutual at 6.00%, and Northwestern Mutual at 5.75% That dividend rate is not the same as your policy’s actual rate of return, since a large share of your early premiums pays for mortality costs, underwriting, and agent commissions rather than building cash value.
Whole term life insurance is not a single product category but people who are searching that phrase are usually comparing the term life insurance, which has no cash value, against whole life insurance which does. Understanding the difference is the first step to answer whether whole life insurance is a good investment for your specific situation.
How Whole Life Insurance Actually Builds Cash Value
Whole life insurance builds cash value through a formula the insurance company controls, not through your own investment choices. Each premium payment is split between the cost of insurance, company expenses, and the cash value account.
Northwestern Mutual describes its process directly: the guaranteed cash value at the start of the year, plus the annual premium, minus a mortality and expense charge, is credited with the company’s current dividend interest rate to produce the year-end accumulated value.The balance is credited with the current dividend interest rate to determine the end-of-year accumulated value Dividends themselves are not guaranteed. They depend on the insurer’s mortality experience, investment returns, and expenses that year.
This is why cash value growth is slow in the early policy years. Most of the growth is designed to compound gradually over decades, not to produce fast returns in year one or two.
Key Takeaways
- Whole life insurance builds cash value through a guaranteed minimum plus a non-guaranteed dividend, not through market-based investment returns.
- 2026 dividend interest rates among major mutual insurers ranged from 5.75% to 6.60%, but that rate is not your actual annual return on the policy.
- Cash value growth is slowest in the early years because premiums first cover insurance costs, underwriting, and commissions.
- Cash value growth inside the policy is tax-deferred under IRS rules, and the death benefit is generally income tax-free to your beneficiary.
Whole Life Insurance vs Term Life Insurance: The Real Cost Difference
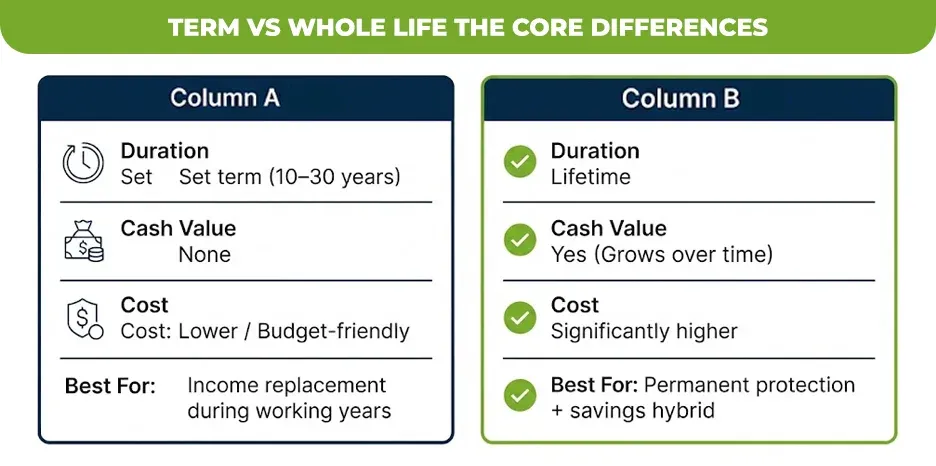
Term life insurance is almost always the cheaper as compared to whole life insurance for the same death benefit because it only covers a set period and build no cash value. Whole life insurance cost more because part of every premium funds a permanent cash value account and lifelong coverage.
| Feature | Term Life Insurance | Whole Life Insurance |
| Coverage length | Set term (10, 20, 30 years) | Lifetime, as long as premiums are paid |
| Cash value | None | Yes, grows over time |
| Premium cost | Lower | Significantly higher for the same death benefit |
| Premium structure | Level for the term, then expires or renews at a higher rate | Level for life |
| Primary purpose | Income replacement during working years | Permanent protection plus a savings component |
| Investment growth potential | None | Modest, guaranteed minimum plus insurer-declared dividends |
This is why financial guidance commonly separates the two questions: whether you need life insurance at all, and whether you need it to also function as a savings vehicle. A whole life insurance policy is a good investment vehicle only if you have already decided you want permanent coverage and are willing to pay more for the savings feature attached to it.
2026 Dividend Rates: What the Top Mutual Insurers Are Paying
Dividend interest rates vary by company and change annually, so the insurer you choose affects your policy’s long-term performance. All five major mutual carriers tracked below raised their dividend interest rate for 2026, the second consecutive year of increases as higher bond yields work into their portfolios.All five mutual carriers raised their dividend interest rate from 2025, a second consecutive year of increases as higher bond yields work into long-duration portfolios
| Insurer | 2026 Dividend Interest Rate | Change vs. 2025 |
| MassMutual | 6.60% | Increased |
| New York Life | 6.40% | +20 basis points |
| Guardian | 6.25% | +15 basis points |
| Penn Mutual | 6.00% | Held steady |
| Northwestern Mutual | 5.75% | Increased |
A higher declared rate does not automatically mean a better policy for you. Policy design, how paid-up additions are structured, and whether the insurer uses direct or non-direct recognition on policy loans all affect what you actually see in your cash value years down the road. Comparing illustrations from an independent insurance broker, rather than a single company’s agent, gives you a clearer side-by-side picture.
When Whole Life Insurance Can Make Sense
Is whole life insurance a good investment for retirement? Well for most of the people, retirement accounts like a 401(k) or IRA, which offer tax advantages specifically designed for the retirement savings and generally lower internal costs, should come first. Whole life insurance can play a supporting role once those accounts are already funded, since its cash value provides a stable, non-market-correlated asset you can borrow against if needed.
Is whole life insurance a good investment for a child? A small policy on a child can lock in low premiums and guarantee future insurability regardless of health changes, which is a protection benefit rather than a growth strategy. It is not designed to fund a child’s college education as efficiently as a 529 plan would.
Whole life insurance also tends to make more sense for wealthy individuals doing estate planning, since the death benefit is generally not included in taxable income and can help cover estate tax liabilities or provide liquidity for heirs.Generally, life insurance proceeds you receive as a beneficiary due to the death of the insured person, are not includable in gross income Business owners funding a buy-sell agreement are another common, legitimate use case where the insurance component matters as much as the savings component.
When Whole Life Insurance Is Not a Good Fit
Why is whole life insurance not a good investment for someone still building basic savings? Because the higher premium crowds out contributions to retirement accounts and emergency savings that typically offer better growth potential and more flexibility. If cash flow is tight, a term life insurance policy paired with disciplined investing usually accomplishes more for less money.
Whole life insurance is also a poor fit if there is any real chance that you will cancel the policy within the first 10 to 15 years. The only cash value growth is limited by underwriting cost and commissions and surrendering a policy early can also mean getting back less as you paid in premium.
Is whole life insurance as a scam or good investment? But it is not a scam when it is so transparently by the license agent the presenting a financial sound, highly rated insurance company but it is frequently oversold as a growth investment when it is better understood as a protection and savings hybrid.
The national Association of insurance commissioners NAIC and each state Department of insurance regulate how these policies must be disclosed and checking insurance companies financial strength rating through AM Best is a reasonable step before committing to a policy that you can hold for the decades.
Tax Treatment of Whole Life Insurance
Understanding the tax rule will help you to clarify why whole life insurance policies are sometimes framed as an investment vehicle. The death benefit that is paid to your beneficiary is generally not counted as taxable income, according to the IRS.Generally, life insurance proceeds you receive as a beneficiary due to the death of the insured person, aren’t includable in gross income and you don’t have to report them
Cash inside the policy tax deferred, it means that you do not have Texas on the growth as long as it stays inside the policy. If you surrender the policy for cash then any amount you receive above what you paid in total premiums is generally taxable as ordinary income. The loans against the cash value are generally not as long as the policy remains enforce and not classified as a modified endowment contract under IRS rules.
How to Decide If Whole Life Insurance Is Right for You
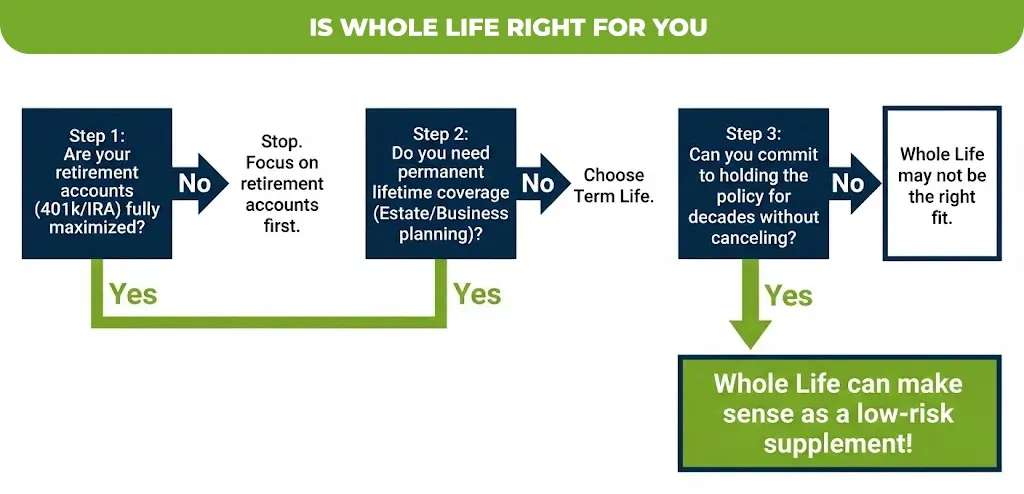
Start by confirming you actually need permanent life insurance, not just coverage for a set number of working years, since that alone determines whether whole life insurance belongs in the conversation at all. If term life insurance covers your real need, such as replacing income until your children are grown or your mortgage is paid off, a whole life policy’s added cost may not be justified purely as an investment.
Next, check whether your retirement accounts are already maximized. Whole life insurance is a good retirement investment supplement, not a replacement, for someone who has already contributed the annual limits to tax-advantaged retirement accounts and wants an additional, low-risk asset.
Finally, get an in-force illustration showing both the guaranteed and non-guaranteed columns from more than one insurer before signing anything. Comparing a single company’s projection against your own goals, rather than against a competitor’s, is where most people make their decision without full context.
Talk to Someone Before You Decide
This article is meant to help you understand the tradeoffs, not to tell you what to buy, and it is not a substitute for advice from a licensed financial advisor or insurance professional who can review your full financial picture. Whole life insurance can be the right tool for specific goals, and the wrong one for others, depending entirely on what you are trying to accomplish.
If you want a straightforward comparison of term and whole life options based on your actual numbers, rather than a single company’s illustration, mlife insurance can walk you through the guaranteed and non-guaranteed figures side by side so you can see what you would actually be buying. You can also read more in our guide to term life insurance basics if you are still deciding what type of coverage you need in the first place.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.