
Cancer diagnosis, a heart attack, or a stroke can arrive without even warning you and a health plan with a high deductible will not even cover your mortgage payment, the last paycheck or the childcare bill that will show up the same month. Buying critical illness insurance without even checking the covered illness list is one of the most common mistakes that people make and it often means discovering the gap only after the claim is denied.
Quick answer
Critical illness insurance pays a lump sum cash benefit directly to you if you are diagnosed with a serious medical event that is named in your policy, and most commonly invasive cancer, heart attack, a stroke, kidney failure or a major organ transplant. The list of covered conditions, the payout amount and the exclusions can be changed by the insurance company and policy. So that the certificate of coverage is the only document that will tell you what your specific plan pays for.
This guide will break down exactly what critical illness insurance covers, what it does not cover, how the payout works and how the group, voluntary and individual plans are different. So that you can check your own policy with confidence instead of guessing.
What Does Critical Illness Insurance Cover?
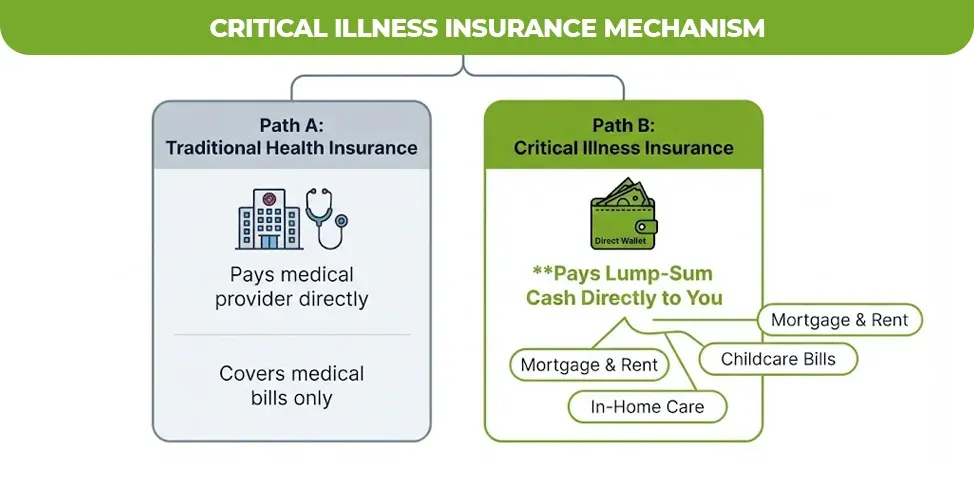
Critical illness covers a fixed list of serious medical diagnosis or the procedures that are named in the policy. And it pays a lump sum benefit once that diagnosis is confirmed. This is different from a health insurance plan which pays providers directly for the specific medical services. According to Anthem, the cash from a critical illness policy is paid to you rather than to the hospital so it can be used for rent, travel treatment, in-home care or any other costs that will come up during the recovery.
The coverage is not universal. Every insurance company set its own list of qualifying illnesses, it’s own definition of severity of each condition and its own pay out rules. That is why the same question, what does critical illness insurance cover you for can have a different answer depending on which insurance company issued the policy.
Key takeaways
- Critical illness insurance pays a lump sum, not a reimbursement tied to medical bills.
- The list of covered conditions is fixed in the policy and varies by insurer.
- Cancer, heart attack, and stroke are the conditions most commonly included across US individual and employer plans, according to Guardian and MetLife.
- Group, voluntary, and individual policies can have different eligibility requirements and payout limits.
- Pre-existing condition exclusions and waiting periods apply to nearly every plan.
What Illnesses Does Critical Illness Insurance Cover?
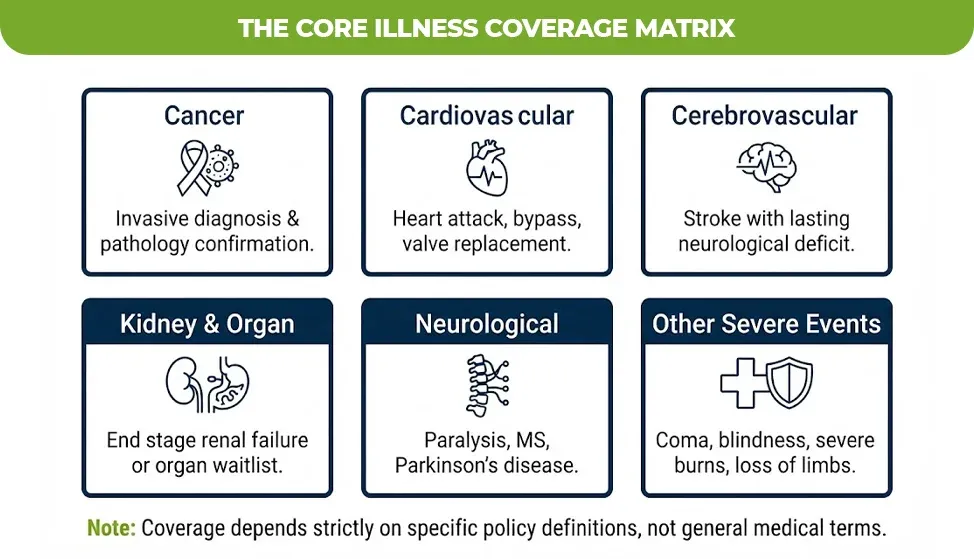
The core illnesses covered by critical illness insurance in the US market generally fall into a small number of categories: cancer, cardiovascular events, organ failure, and a set of severe neurological or physical conditions. The table below lists the categories that appear across individual and employer-sponsored critical illness plans described by Guardian, MetLife, and Anthem.
| Condition Category | Example Qualifying Events | Typical Payout Trigger |
| Cancer | Invasive cancer diagnosis, in some plans certain non-invasive or recurring cancers | Confirmed pathology report meeting the policy’s severity definition |
| Cardiovascular | Heart attack, coronary artery bypass surgery, heart valve replacement | Diagnosis or surgery matching the policy’s clinical definition |
| Cerebrovascular | Stroke with lasting neurological deficit | Confirmed stroke diagnosis meeting duration and severity requirements |
| Kidney and organ | End stage renal failure, major organ transplant, being placed on a transplant waiting list | Diagnosis or transplant procedure confirmed by a physician |
| Neurological | Paralysis, multiple sclerosis, Parkinson’s disease, motor neuron disease | Diagnosis confirmed by a specialist |
| Other severe events | Permanent blindness, deafness, coma, severe burns, loss of limbs | Diagnosis or event meeting the policy’s permanence requirement |
What Does Critical Illness Insurance Not Cover?
Every critical illness policy has exclusions and eligibility requirements that limit when a claim will be paid. The most common ones are consistent across the industry.
- Pre-existing conditions. Most policies exclude a condition diagnosed or treated in the months before the policy started, typically for a defined look-back and waiting period.
- Survival period. Many policies require the insured to survive a set number of days, often between 14 and 30, after diagnosis before the benefit pays out.
- Severity thresholds. A diagnosis that does not meet the policy’s specific clinical definition, such as an early-stage cancer excluded from a policy that only covers invasive cancer, will not trigger payment.
- Conditions not named in the policy. If an illness is not on the covered list, it is not covered, regardless of how serious it is.
- Waiting periods. Coverage for illness (though usually not for accidental injury) commonly does not begin until 30 to 90 days after the policy is issued.
Reading the policy’s definitions section, not just the marketing brochure, is the only reliable way to confirm eligibility requirements before a claim is needed.
Group Critical Illness Insurance Coverage vs Voluntary Critical Illness Insurance Coverage
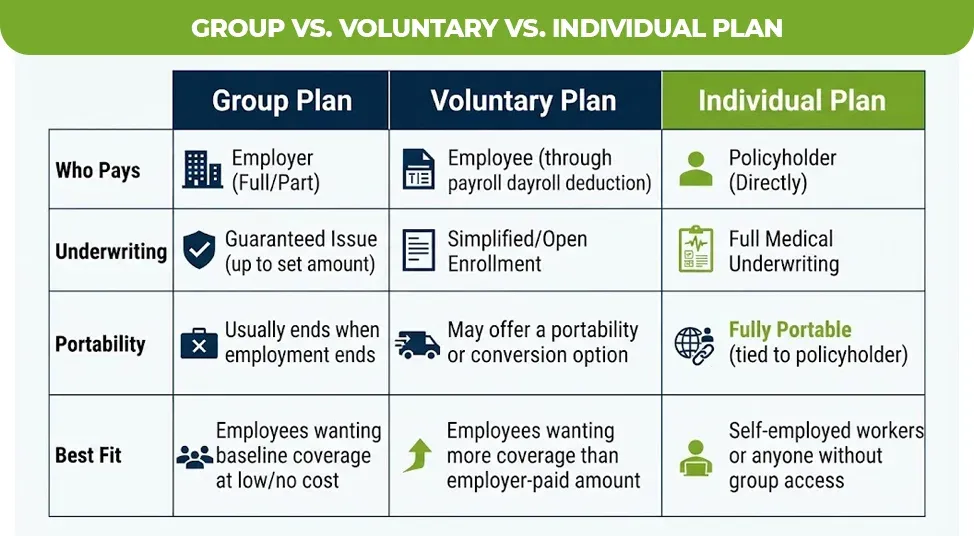
Critical illness insurance is sold through three main channels in the United States. These are employer sponsored group plans, voluntary plans that are offered by an employer but paid for by the employee and the individual policies that are purchased directly from an insurance company or broker. The difference is affect underwriting, cost and portability.
| Feature | Group Critical Illness Insurance | Voluntary Critical Illness Insurance | Individual Critical Illness Insurance |
| Who pays the premium | Employer, in full or in part | Employee, through payroll deduction | Policyholder directly |
| Underwriting | Often guaranteed issue up to a set benefit amount | Simplified or guaranteed issue during open enrollment | Full medical underwriting is common |
| Portability | Usually ends when employment ends | May offer a portability or conversion option | Fully portable, tied to the policyholder |
| Benefit amount | Often a fixed, modest amount set by the employer | Employee can typically choose from a few benefit tiers | Benefit amount is chosen at application |
| Best fit for | Employees wanting baseline coverage at low or no cost | Employees wanting more coverage than the employer-paid amount | Self-employed workers or anyone without group access |
Critical Illness Life Insurance Coverage: How It Differs From a Standalone Policy
Critical illness benefits are not only sold as a standalone policy. Many insurers offer critical illness life insurance coverage as an accelerated benefit rider attached to a permanent or term life insurance policy. In that structure, a covered diagnosis lets the policyholder access a portion of the life insurance death benefit while still alive, and the remaining death benefit is reduced by whatever amount was paid out.
Does Critical Illness Insurance Cover Your Spouse and Family?
Critical illness for spouse and dependent coverage is available on most of the groups, voluntary and individual policies but it is automatic. In an employer sponsored plan, the employee generally has to actively elect the spouse at child coverage during enrollment and the benefit amount for a spouse is often set at a percentage of the employee benefit that is commonly 50%. The individual policies sold directly to the consumers usually required the spouse to apply and undergo underwriting separately or to be added as a covered person with their own qualifying illness list.
How Much Does Critical Illness Insurance Pay, and How Is the Benefit Used?
The critical illness benefit is paid as a single lump sum benefit once a covered diagnosis is confirmed and any survival period is me. The common benefit amounts for the individual and the voluntary plan generally range from a few thousand dollars up to $50,000 or even more. And it is choosing at the time of enrollment or application. There is no requirement to submit the receipt or itemize how the money is spent, that is what separates the critical illness insurance payout structures from the standard health insurance reimbursement.
Final Thoughts on What Critical Illness Insurance Covers
Critical illness insurance can provide real financial breathing room after a serious diagnosis but only if the policies covered conditions, exclusions and benefit amount actually match your situation. The safest approaches are to request a full list of covered conditions and the definitions section before you buy, not just the marketing summary, and to compare the group, with entry entry and individual options side-by-side. If you already have life insurance and want to understand how a critical illness rider would affect your existing death benefit, our life insurance coverage guide walks through how accelerated benefit riders work in more detail.
If you are thinking whether critical illness coverage fits alongside a term or whole life policy, a licensed advisor at Mlife Insurance can walk through your existing coverage with you and point out any real gaps, with no pressure to buy anything on the spot.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.