
How Much Does Single Premium Term Insurance Cost?
The cost is the insurance company’s calculation of the whole term’s premiums, collected in one payment. It depends on your age, health, coverage amount and term length, and each insurer uses its own pricing assumptions.
Ethos lists the main factors and that younger applicants can qualify for lower rates, tobacco use and health conditions can also raise the price, and longer terms and higher coverage amounts increase the upfront cost. No universal rate chart exists. Any dollar figure that appears without an age, health class, term and insurer attached should be treated with caution.
Rates and quotes. Single premium term insurance rates are not published in a single standard table. The only reliable way to get a single premium term insurance quote is to request one from an insurer or a licensed agent, using the same age, term and coverage amount for every request.
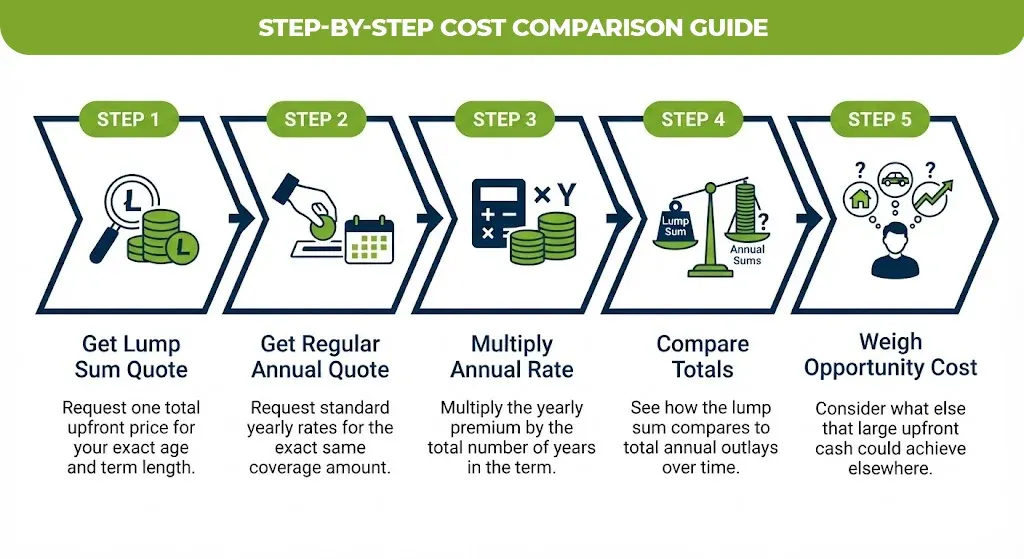
A simple cost comparison method. If you cannot find a dedicated single premium term insurance cost calculator, you can build a fair comparison yourself:
- Get a quote for one lump sum for your age, term and coverage amount.
- Get a quote for regular annual premiums for the same policy.
- Multiply the annual premium by the number of years in the term.
- Compare the two totals, and note how long the lump sum would have lasted at the annual rate.
- Consider what else you could do with the lump sum.
What Are the Benefits and Drawbacks of Single Premium Term Life Insurance?
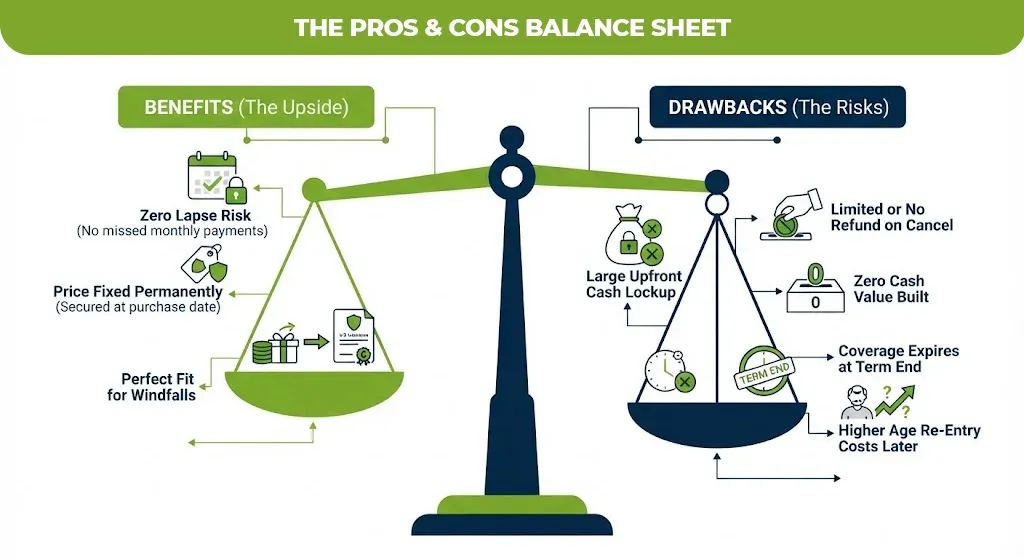
The main benefit is certainty. You have to pay once, the coverage is prepared in the policy cannot labs from a missed payment. The main drawback is that you commit a large sum to coverage that has no cash value and no guarantee return.
Benefits of single premium term life insurance
- No lapse risk from missed payments. Once the premium is paid, there is nothing to forget.
- Simple structure. There is no cash value to track and no investment choice to manage.
- Price fixed at purchase. The premium reflects your age and health when you buy.
- Fit for windfalls. An inheritance, bonus or sale of an asset can be turned into protection for a defined period.
The 4 drawbacks to weigh
- Large upfront payment. You need the full amount available, and you lose access to that money for other goals. This is the opportunity cost.
- Limited or no refund. Cancel early and you usually do not recover the unused portion.
- No cash value. Permanent policies build value that you can borrow against or withdraw. But the term does not.
- Coverage ends at the end of the term. If you still need protection, you must apply again at an older age, and rates may be higher.
Who Should Consider It, and Who Should Skip It?
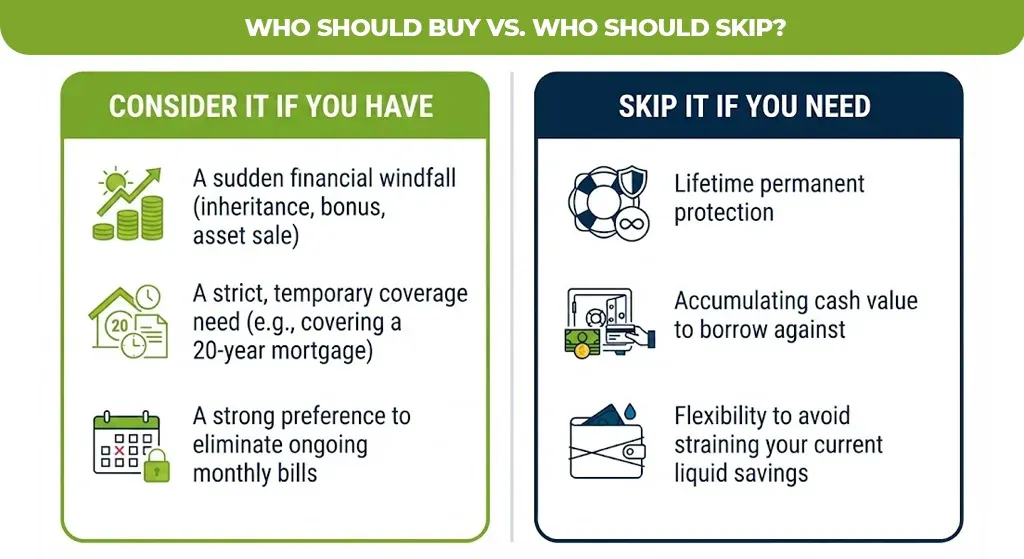
Single premium term life insurance fits people who have a lump sum, a temporary need and a reason to avoid ongoing payments. It fits poorly for people who would strain their budget to pay it or who need lifetime coverage.
Consider skipping it if any of these apply:
- You need lifetime coverage. A permanent policy fits better.
- You want cash value. Whole life or universal life builds it, though a single lump sum into these policies often creates a MEC.
- You would strain your finances to pay it. Regular term premiums may be more workable.
- You expect your needs to change. A convertible term policy may offer more flexibility.
How Do You Find the Best Single Premium Term Insurance Policy and Companies?
There is no single best single premium insurance policy for everyone. The right choice is one that matches your term, your budget, and health class interest. And also that comes from a financially stable insurance company that actually offers a prepaid option.
Because fewer single premium term insurance companies offer this structure, start by confirming availability. A licensed agent can check which carriers in your state accept a lump sum for a term policy. You can also verify an agent or insurer’s license with your state department of insurance, which the NAIC helps connect through its consumer resources.
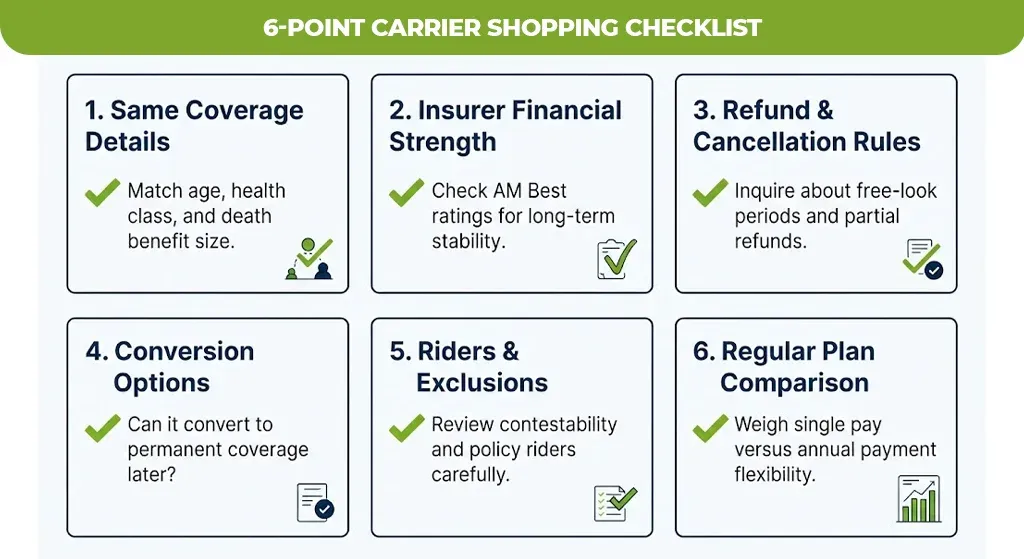
Then compare offers using the same inputs. A useful checklist:
- Same coverage details. Use the same death benefit, term length, age and health class for every quote.
- Insurer strength. Review the insurer’s financial strength rating from an independent agency such as AM Best. The rating reflects the insurer’s ability to meet its obligations.
- Refund and cancellation rules. Ask whether any portion of the premium is refundable, and what the free-look period is in your state.
- Conversion option. Ask whether the term policy can be converted to permanent coverage before it expires.
- Riders and exclusions. Review riders, exclusions and the contestability period, which is set by policy terms and state law.
- Alternatives. Compare the total cost with a level term policy paid annually or monthly.
Also compare the single premium term insurance plan with a regular term plan of the same length. If the lump sum saves little compared with regular premiums, the flexibility of paying over time may be worth more than the convenience of paying once.
A note on wording: you may see single premium term insurance plans described as “best” or “top” on comparison pages. Treat those labels as marketing unless the ranking method and data are explained.
If you are weighing a lump sum against regular premiums, it helps to compare real quotes side by side. The team at Mlife insurance can walk through your options with no pressure, and there is no obligation to buy anything.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.