
Choosing limited pay whole life insurance because “the premiums end in 10 years” can be an expensive mistake if you have not checked what the higher payments do to your budget. If you miss payments during the premium payment period, the policy can lapse or shrink. Years of premiums may then buy far less coverage than you expected.
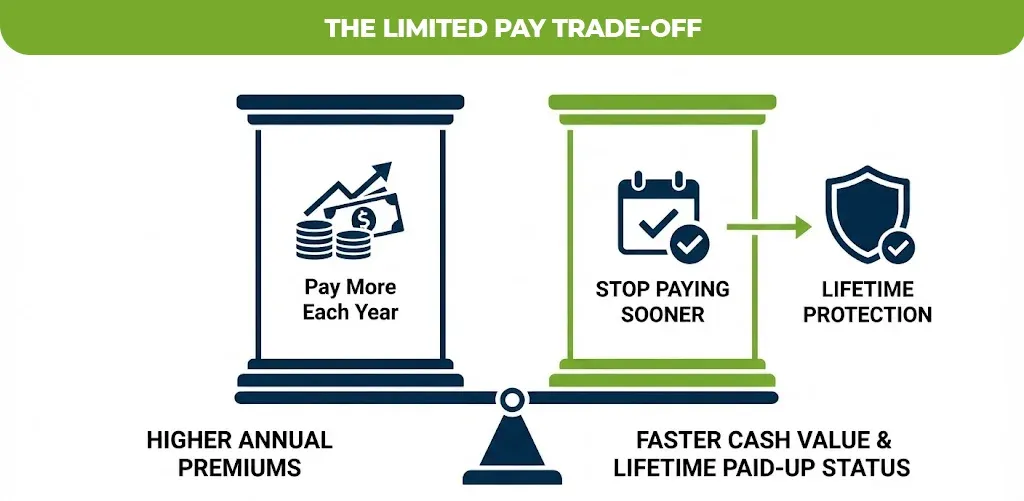
Limited pay life insurance is a permanent life insurance policy where you pay premiums for a certain number of years such as, 15, or 20. And the death benefit will stay active for your whole life. The trade is very simple. You pay more each year and you stop paying sooner.
Quick Answer
A limited payment whole life insurance policy provides lifetime coverage, guaranteed death benefit and also cash value. But you pay premiums over a short period than with ordinary whole life. The national Association of insurance commissioners says that these policies have higher premiums as compared to the ordinary whole life and build cash value faster. The main trade off is affordability during the payment period and possible tax treatment as a modified endorsement contract if premiums are too high too fast.
Key Takeaways
- Shorter payment periods mean higher annual premiums for the same death benefit.
- Stopping payments early triggers a non-forfeiture option, which is usually a smaller paid-up policy or extended term coverage.
- Funding a policy in seven years or fewer can cause MEC status under IRS rules.
- Any cost example you see online is only a rough guide. Ask an insurer for a personalized illustration.
What Is Limited Pay Whole Life Insurance?
It is whole life insurance with a fixed premium payment period instead of premiums for life. The NAIC describes limited payment whole life insurance as a policy where premiums are paid over a shorter time while coverage lasts a lifetime. It adds that these policies build cash value faster and have higher premiums than ordinary whole life, and that they may be participating or nonparticipating.
A limited payment whole life policy provides three things. It provides a death benefit that your beneficiary receives when you die. It provides cash value that builds inside the policy. It also provides a paid-up policy status once you finish the last premium, which means no more life insurance premiums are due.
The label “limited pay” describes only the premium payment period, not the coverage period. Coverage in a limited pay life insurance policy continues for life as long as premiums were paid as scheduled. The names limited pay life, limited payment life insurance, and limited pay life insurance policy all describe the same basic design.
Participating policies may pay dividends. The NAIC notes that dividends can lower premiums or buy more coverage, and that dividends are based on the insurer’s financial performance and are not guaranteed.
Here is how this differs from term coverage. The NAIC states that term life insurance pays a death benefit only if the insured dies during the term, commonly 1, 5, 10, or 20 years. Term is generally more affordable early on. A limited pay whole life policy is permanent life insurance, so it has no expiration date.
How Do 10 Pay, 15 Pay, and 20 Pay Policies Compare?
A shorter premium payment period means a higher annual premium and faster cash value growth. The table below compares typical structures for the same death benefit, age, and health rating.
| Feature | 10 pay whole life | 15 pay life insurance | 20 pay whole life | Ordinary whole life |
| Premium payment period | 10 years | 15 years | 20 years | Lifetime, or to the policy’s stated maturity age |
| Annual premium | Highest of the four | Lower than 10 pay | Lower than 15 pay | Lowest of the four |
| Cash value growth | Fastest | Fast | Moderate | Slowest of the four |
| Coverage after payments end | Lifetime, paid up | Lifetime, paid up | Lifetime, paid up | Requires continued premiums |
| Budget pressure | Highest early on | High | Moderate | Lowest per year |
The ordering follows from the limited pay policies are built. Each policy must fund the same lifetime benefit so that fewer payments are required larger payments. The actual rates can be changed and different by insurance company, age, health class and death benefit so that no table can replace a quote.
Some insurers also sell limited pay designs that end at a target age, such as age 65. A 10 pay life insurance policy bought at 30 finishes at 40. A 20 pay life policy bought at 45 finishes at 65, which is why some buyers use it to align premiums with retirement.
Is There a Tax Catch With Shorter Payment Periods?
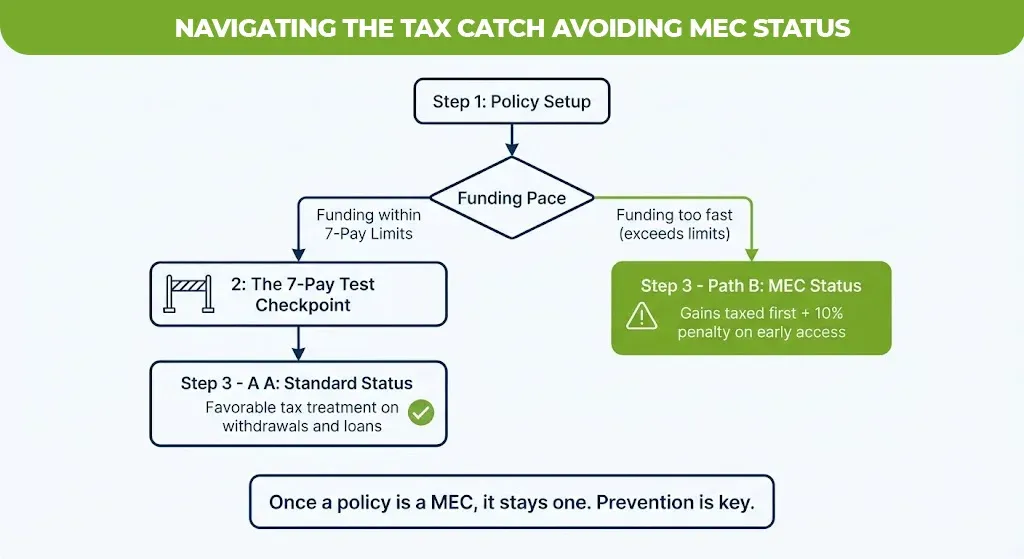
Yes. If you pay premiums too quickly, the policy can become a modified endowment contract (MEC), which changes how withdrawals and loans are taxed. The IRS 7-pay test in Section 7702A says a policy fails if the amount paid during the first seven contract years exceeds the net level premiums that would have fully paid up the contract in seven level annual payments.
That means a single premium or a five pay design would generally fail the test. A 10 pay or 20 pay whole life policy is designed with lower annual premiums than the 7-pay limit at ordinary funding levels. However, paying extra through paid-up additions or increasing premiums in the early years can push a policy over the line. Ask the insurer to confirm the MEC status in writing and to tell you the 7-pay limit.
MEC status has real consequences for access to your cash value. According to LegalClarity’s summary of Section 7702A, withdrawals, loans, and pledges from a MEC face income tax on gains first and a potential 10 percent penalty, whereas a standard policy allows more favorable tax treatment. Once a policy is a MEC, it stays one, so prevention matters more than correction.
The death benefit is treated differently. The IRS states that life insurance proceeds paid because of the insured person’s death are generally not includable in gross income. Interest earned on proceeds can be taxable, and estate tax rules can apply in some situations, so review your plan with a tax professional.
What Happens If You Stop Paying Before the Policy Is Paid Up?
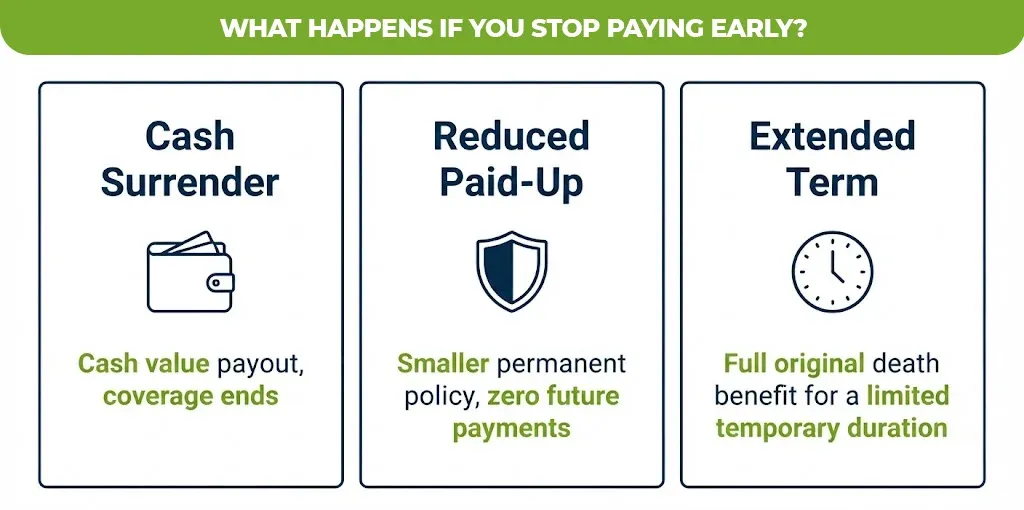
If you stop paying early, the insurer must offer a non-forfeiture option, and your choice determines how much protection remains. The NAIC explains that state laws require whole life policies to include nonforfeiture values. These are benefits paid in cash or other insurance options if the policy ends because of missed payments or surrender.
The NAIC Life Insurance Buyer’s Guide (New Jersey edition reprint) adds that you can use cash value to keep protection for a limited time, or to buy a reduced amount without paying more premiums. The three usual options are shown below.
| Non-forfeiture option | What you get | Best understood as |
| Cash surrender | The cash surrender value, and coverage ends | Ending the policy |
| Reduced paid-up option | A smaller, permanent policy with no further premiums | Reduced paid-up life insurance |
| Extended term | Full original death benefit for a limited period, then coverage ends | A temporary coverage swap |
Who Should Consider Limited Pay Whole Life, and Who Should Skip It?
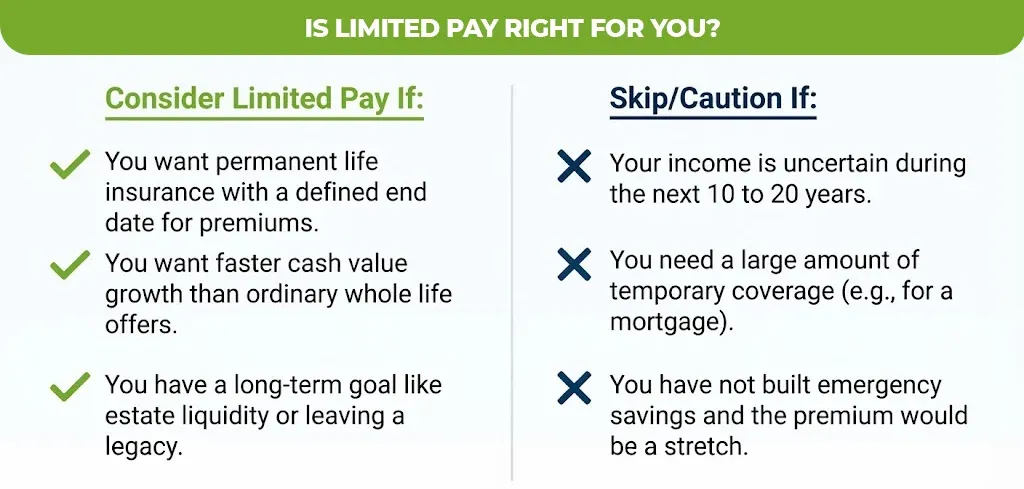
These situations often make it worth considering:
- You want permanent life insurance with a defined end date for premiums, such as before retirement.
- You want faster cash value growth than ordinary whole life offers.
- You have a long-term goal such as estate liquidity, final expenses, or leaving a guaranteed legacy to beneficiaries.
These situations call for caution:
- Your income is uncertain during the next 10 to 20 years.
- You need a large amount of coverage for a temporary need, such as a mortgage or children’s dependence years. Term coverage may cover that need at a lower cost.
- You have not built emergency savings and the premium would be a stretch.
A Practical Next Step
If you are still comparing, request the same death benefit quoted as a 10 pay, a 20 pay, and an ordinary whole life policy. Seeing all three side by side, with guaranteed values shown separately, often clarifies the decision more than any general article can.
If you would like a neutral second look at the numbers, the team at MLife Insurance can walk you through the options without pressure. You can talk to the Mlife Insurance team and ask questions before you decide.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.