
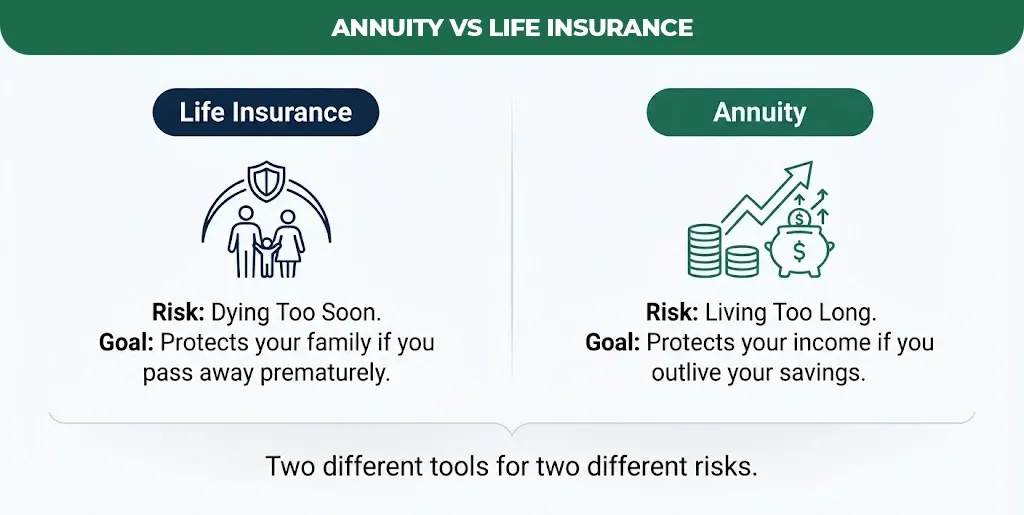
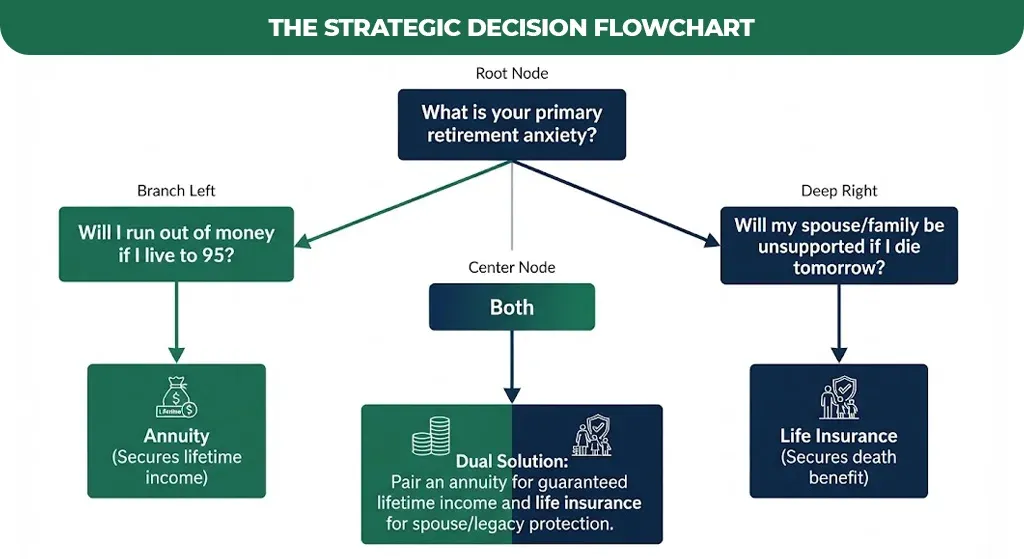
A lot of people hear that annuities and life insurance or insurance products and assume that they both do the same job. But actually they do not. One protects your family if you die too soon and the Other protects your income if you live a long time.
Buying the wrong one and leaving your spouse without protecting or leave you worried about running out of money. We will explain annuity vs life insurance so that you will understand the cost, taxes, death benefit and the decision guide.
Annuity vs Life Insurance: What Is the Core Difference?
Life insurance is specifically built for the risk of dying too early. And annuity is built for the risk of living too long. That is a simple way to compare annuity vs life insurance policy.
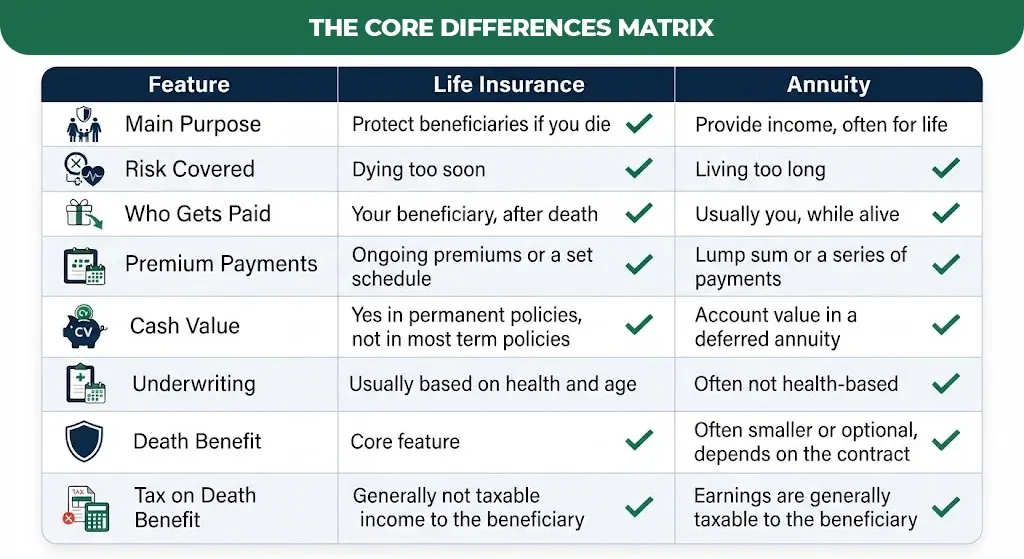
Annuity vs life insurance differences at a glance
| Feature | Life insurance | Annuity |
| Main purpose | Protect beneficiaries if you die | Provide income, often for life |
| Risk covered | Dying too soon | Living too long |
| Who gets paid | Your beneficiary, after death | Usually you, while alive |
| Premium payments | Ongoing premiums or a set schedule | Lump sum or a series of payments |
| Cash value | Yes in permanent policies, not in most term policies | Account value in a deferred annuity |
| Underwriting | Usually based on health and age | Often not health-based |
| Death benefit | Core feature | Often smaller or optional, depends on the contract |
| Tax on death benefit | Generally not taxable income to the beneficiary | Earnings are generally taxable to the beneficiary |
Life Insurance vs Annuity for Retirement Income
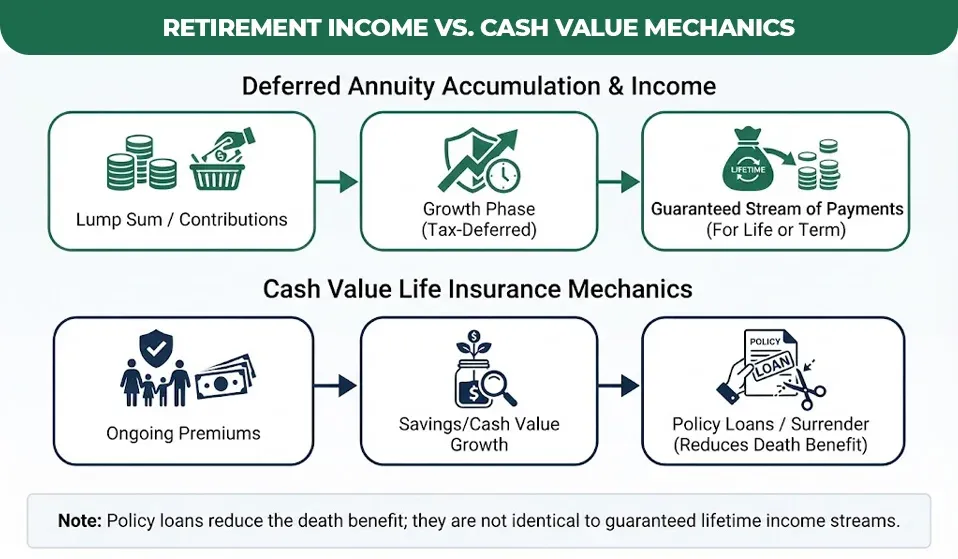
For retirement income, an annuity is specifically able to provide the payments, while life insurance is built to provide benefit. Some permanent life insurance policies also build cash value that you can borrow later but that is not the same as the guaranteed income stream.
How annuity income works
An annuity turns a lump sum a series of payment to include the income. A deferred annuity will grow first and pay later. An immediate annuity start being soon after you find it. The payments can last for a set time or for your lifetime depending on the option that you choose.
How cash value life insurance fits
Cash value life insurance such as whole life insurance and universal life insurance has a saving component that will grow inside the policy. You can borrow against the tour and surrender the policy, which can reduce the death benefit or end coverage. The NAIC buyers guide noted that whole life and universal life insurance that type of cash value insurance while most term policies do not have any cash value.
Using a cash value for retirement income convert for some household but it is not the same as guaranteed lifetime income. Make sure to ask the insurance company how loans and withdrawal affect the policy.
Retirement annuity vs life insurance: how they can work together
Some households use an annuity for income that they cannot outlive and a life insurance policy to protect spouses or leave money to their beneficiaries. This is a planning choice not a rule. A licensed agent or fee only financial planner will help you to compare the combination.
Annuity Types vs Life Insurance Types: Which Compares to Which?
Match the type of annuity to the type of life insurance based on the goal you are comparing. The wrong comparison causes confusion, so use this guide.
| If you are comparing | Key difference |
| Annuity vs term life insurance | Term life covers a fixed time and it pays only if you die in that time An annuity pays income and is not a pure death protection product. |
| Annuity vs whole life insurance | Whole life insurance can cover you for your entire life and it also build cash value. While annuity totally focus on the income and growth for the retirement. |
| Annuity vs universal life insurance | Universal life has flexible premiums and cash value. An annuity has an account value and income options. |
| Fixed annuity vs life insurance | A fixed annuity earns a stated interest rate. Life insurance pays a death benefit. |
| Variable annuity vs variable life insurance | Both plans invest in market-based sub accounts and carry investment risk. A variable annuity focus on the retirement income, and variable life focuses on a death benefit. |
| Deferred annuity vs life insurance | A deferred annuity grows first and pays later. Life insurance pays after death |
Annuity Death Benefit vs Life Insurance Death Benefit
Life insurance therapy benefit is the main reason to buy the policy while an annuity that benefit is optional and it is also limited to the features that depends on the contract. What happens to an annuity when you die depends totally on the stage of the contract in the payout options that you choose.
Under a life only income option, the payment can stop at death with nothing left for the family or beneficiaries. A time certain, cash refund or joint and survivor options can continue the payments to the beneficiary of the surviving spouse. This is the time where are survivor annuity vs life insurance comparison matter a lot like a survivor option can protect a spouse income. But it usually lowers the monthly payments while you are still alive.
Costs, Fees, and Taxes: What to Compare
You can compare costs by looking at premiums, fees, surrender charges, and tax payments not just the headline number. Annuities and life insurance both have trade-offs.
Life insurance costs
- Generally term life costs less as compare permanent life insurance plans for the same death benefit. Whole life and universal life cost more and build cash value.
- Insurers review your age and health to set the price.
- Optional add-ons can also increase the cost.
Annuity costs
- The NAIC deferred annuity guide explains that withdrawals during the surrender period can trigger charges.
- Variable annuities can include investment fees, insurance charges, and rider fees.
- Taking money out before the age 59 can also trigger an additional 10% charges for federal tax on the portion that is taxable with exceptions.
Taxes on growth
Annuity growth is generally tax-deferred, but withdrawals of earnings are taxed as ordinary income. Cash value in a permanent life insurance policy also grows without annual income tax while it stays in the policy..
A Simple Next Step
Write down your answer to one question: “If I die tomorrow, who needs money, and if I live to 95, will my income last?” Your answer will show whether you need life insurance, an annuity, or both. For a plain-language explanation of life insurance types and how they fit into a plan, Mlife insurance’s guides are a helpful place to start.
Joyce Espinoza, Expert Life Insurance Agent
Joyce Espinoza is a trusted life insurance agent at mLifeInsurance.com. She’s been in the insurance industry for over ten years, helping people, especially those with special health conditions to find the right coverage. At MLife Insurance, Joyce writes easy-to-understand articles that help readers make smart choices about life insurance. Previously, she worked directly with clients at Mlife Insurance, advising nearly 3,000 of them on life insurance options.